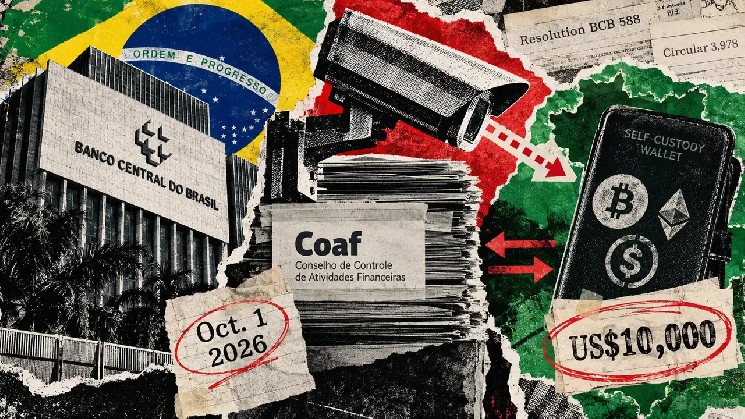
The brink operates mechanically. Establishments don’t want to find out {that a} transaction is suspicious earlier than submitting a report, which means legit transfers between an alternate and a buyer’s private pockets can enter Coaf’s reporting system solely as a result of they meet the quantity and transaction-type standards.
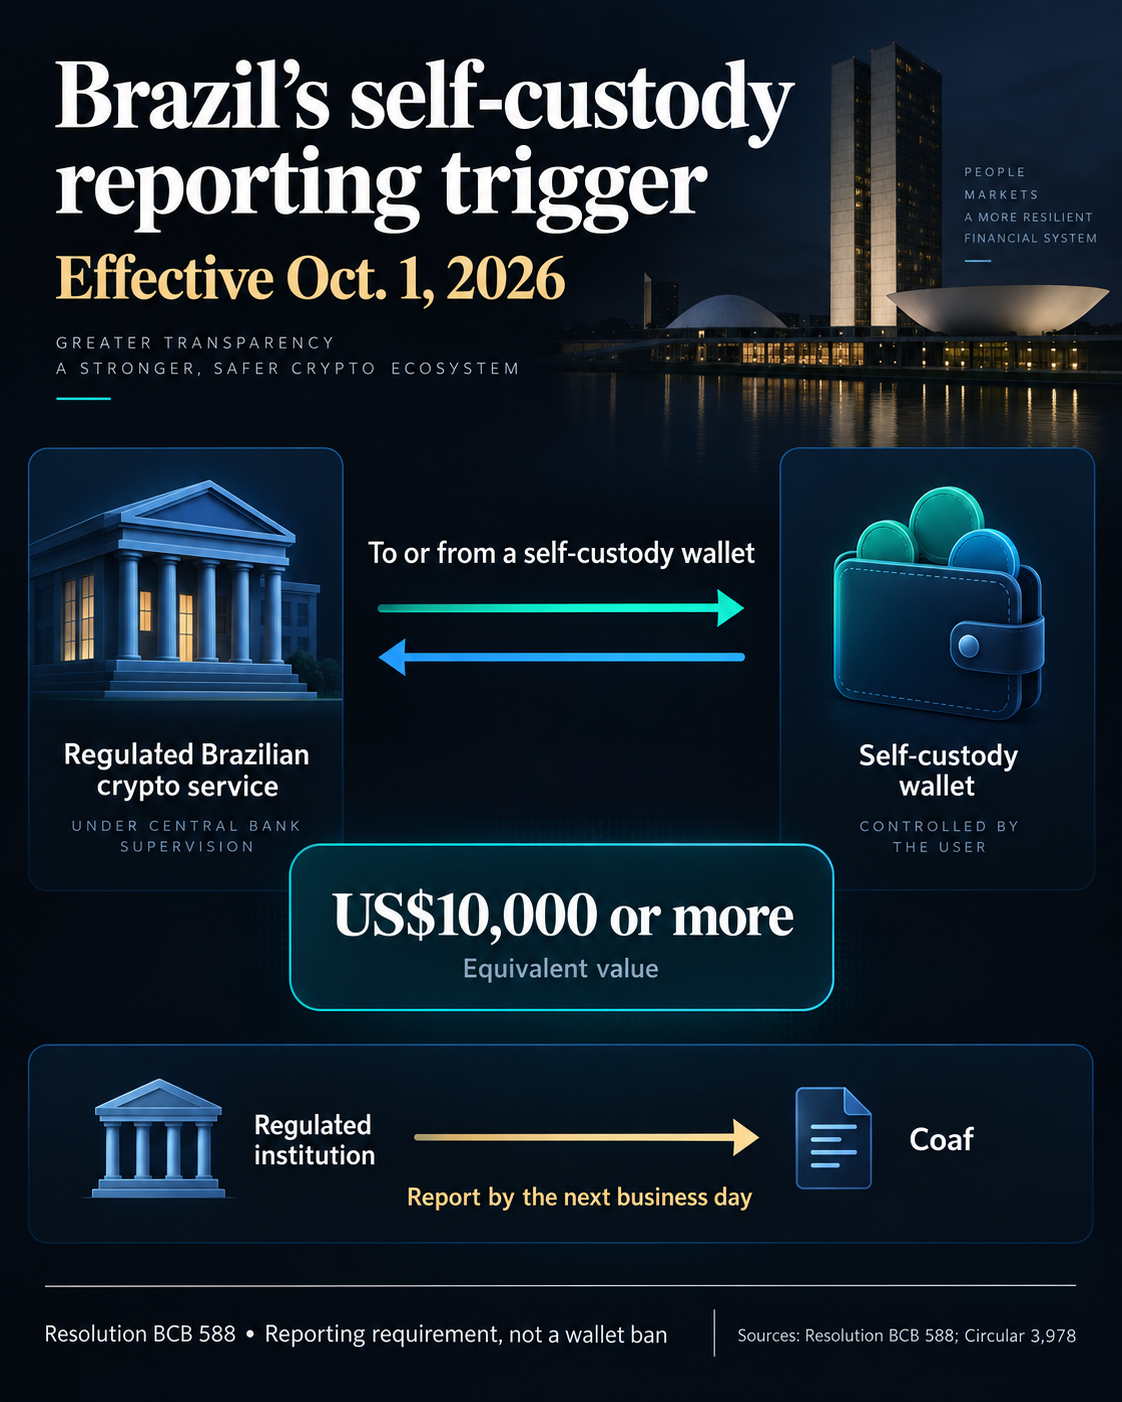
Brazil already requires monetary establishments to individually report transactions they assess as suspicious.
The brand new provision provides one other layer by giving authorities visibility into massive actions crossing the boundary between regulated platforms and self-custody, even the place no suspicious exercise has been recognized.
The October measure additionally precedes tighter controls on some outbound crypto transfers.
Decision BCB 584, scheduled to take impact Jan. 1, 2027, establishes a precautionary holding process for sure virtual-asset transfers leaving regulated establishments. These transactions could also be delayed whereas extra checks are carried out, though the framework permits earlier launch the place specified situations are met.
Collectively, the measures enhance scrutiny on the level the place crypto enters or leaves Brazil’s regulated monetary system.
Exchanges, banks and different lined suppliers might want to determine self-custody counterparties, calculate transaction values and combine computerized Coaf reporting into their monitoring programs earlier than the October deadline. By January, some may also want processes that may maintain outbound transfers for additional overview.
Guidelines land as Brazil’s crypto market expands
The more durable oversight is being launched in one of many world’s largest crypto markets.
Brazil accounted for $252.5 billion of crypto exercise through the interval measured by Chainalysis, giving it the most important market in Latin America and serving to it rank first within the agency’s 2026 international crypto adoption index.
That rating displays broad participation quite than dominance in each class. Brazil positioned third in flows by crypto providers, fourth in on-chain balances, third in home peer-to-peer exercise, and second in cross-border flows. The US ranked second total.
The size of these flows makes the self-custody threshold commercially important. Excessive-value customers, buying and selling companies, and companies that recurrently transfer property between regulated platforms and personal wallets usually tend to set off computerized regulatory filings, whereas exchanges will bear the operational value of figuring out and reporting them.
Brazil’s measured crypto financial system however contracted 1.6% through the newest interval, exhibiting that the regulatory growth is arriving at the same time as near-term exercise has cooled.