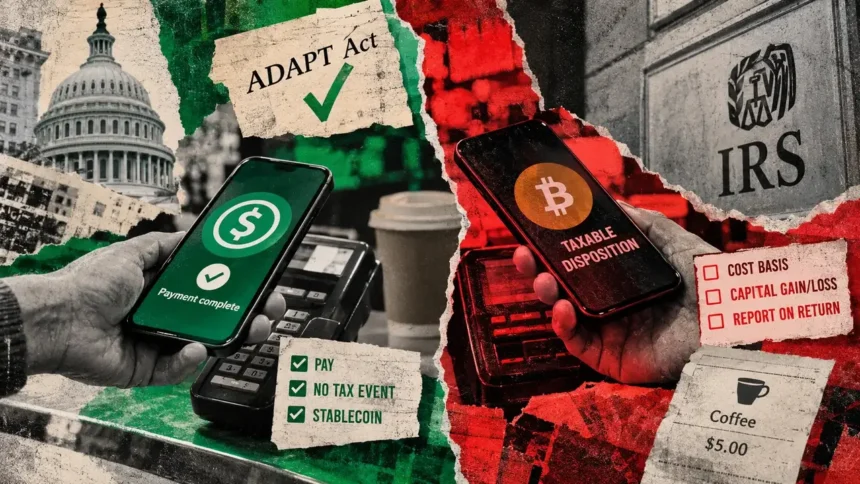
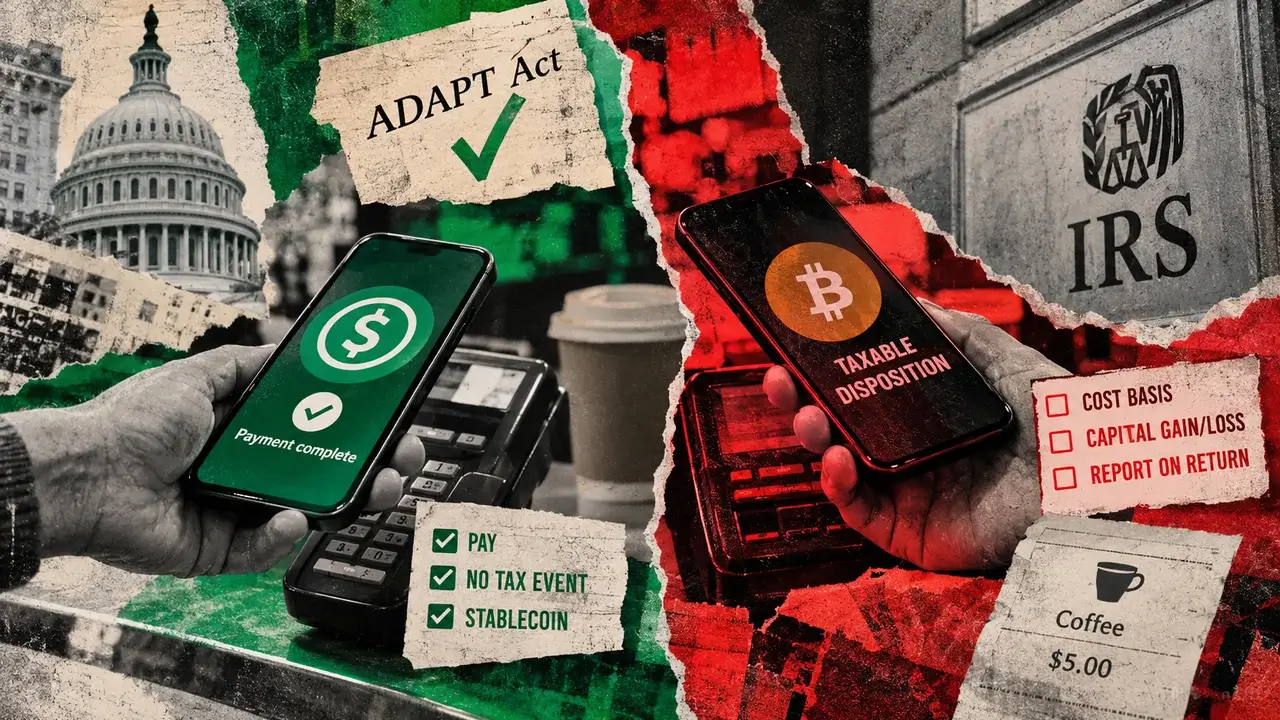
A espresso purchased with a qualifying greenback stablecoin would keep away from gain-or-loss recognition beneath the ADAPT Act that Sen. Steve Daines launched Sept. 30. The identical espresso purchased with Bitcoin would nonetheless set off the cost-basis calculation and capital achieve or loss reporting that connect to spending digital property.
Bloomberg Regulation reported Sept. 25 that Daines had circulated a draft and anticipated to introduce it the subsequent week. The 56-page textual content launched Sept. 30 carries the title Aligning Digital Belongings with Rules of Taxation Act and lists Sens. Cynthia Lummis, Bernie Moreno and Tim Scott of South Carolina as cosponsors.
Beneath present IRS steerage, paying for items or providers with digital property in any quantity is a disposition. Holders of private or funding property should calculate and report capital achieve or loss, which is determined by the asset’s worth and value foundation.
A fee can produce a achieve, a loss, or a break-even outcome, and the IRS makes use of a cup of espresso as its personal instance. A $5 Bitcoin buy with an allotted foundation of $3 produces a $2 capital achieve that belongs on the return.
What qualifies as a coated stablecoin
New part 1034 of the tax code would deal with the disposition of coated fee stablecoins to purchase services or products as a nonrecognition occasion. The reduction covers achieve or loss on the token itself, and gross sales taxes and different buy obligations keep in place.
The token should be a certified US greenback stablecoin, that means one issued by a permitted fee stablecoin issuer beneath the GENIUS Act.
A international issuer qualifies by way of OCC registration or a Treasury discovering that its dwelling regime is comparable. It should seem in Treasury’s most up-to-date report earlier than the fee, and the taxpayer should have acquired it at a worth inside 3% of $1.00.
Treasury would publish that report at the least each three months, itemizing every certified stablecoin actively traded inside 3% of $1.00 through the 12 months ending the prior month. Customers and fee firms would examine the most recent listing when making a purchase order.
Merchants, brokers, and sellers in certified greenback stablecoins are excluded, together with taxpayers utilizing a purposeful foreign money apart from the greenback, and Treasury might prolong the trade-or-business exclusion to comparable companies.
Taxpayers should hold data that distinguish eligible funds from different transactions. Lined funds can be exempt from dealer data returns beneath part 6045(i)(1), and brokers might depend on buyer certifications and skip verifying the three% acquisition check for tokens purchased elsewhere. The stablecoin provision applies to transactions entered into beginning Jan. 1, 2027.
Bitcoin retains its paperwork, with one charge carve-out
Part 1034 covers stablecoins, so a Bitcoin fee at checkout stays a taxable disposition, whereas Part 11 provides a narrower rule for charges.
Beneath new part 1044, cash disposed of to pay digital asset transaction prices would escape gain-or-loss recognition when the combination worth of the property used for these prices is $10 or much less. Base, gasoline, and precedence charges depend as prices, and associated transactions are aggregated.
Exclusions apply to merchants, brokers and sellers, companies that batch transactions or assist validate them for others, and property beneath mark-to-market accounting. Anybody who initiated greater than 5,000 digital asset transactions within the prior taxable yr can be excluded.
The charge exception takes impact for inclinations beginning Jan. 1, 2027, the identical date because the stablecoin reduction. On a Bitcoin espresso, the sliver of BTC paid as a community charge might qualify, and the cash despatched to the service provider stay a taxable disposition.
The invoice additionally exempts certified greenback stablecoins from the wash-sale and constructive-sale guidelines it extends to different digital property.
Earlier payments used greenback thresholds
Earlier proposals sought to scale back tax friction for qualifying private crypto transactions by way of financial thresholds.
Sen. Ted Budd’s S.4171, launched March 24, would require each transaction worth and in any other case acknowledged achieve or loss to be $200 or much less. Associated transactions can be aggregated, with exclusions together with business-property and cash-equivalent exchanges.
Lummis’s S.2207, unveiled in July 2025, units a $300 ceiling on each transaction worth and acknowledged loss and ends additional exclusions as soon as qualifying annual positive aspects exceed $5,000.
The Home PARITY Act proposed a $200 threshold for stablecoin transactions. Lummis now cosponsors a textual content that ties reduction to eligible stablecoins at any buy dimension.
The Home has a separate proposal. H.R.10357 was launched Sept. 14, and Methods and Means introduced committee approval by 38-5 on Sept. 16. Its stablecoin redemption-value accounting and qualifying $10 charge reduction are distinct mechanisms, and committee approval is a step earlier than any Home vote.
What occurs subsequent for stablecoin and Bitcoin
These stay proposals, and present IRS remedy stays in pressure. The textual content leaves Treasury to set the mechanics, together with the quarterly listing, recordkeeping, and dealer reporting guidelines. It borrows its issuer definitions from the GENIUS Act, so which tokens qualify will comply with issuer approvals beneath that legislation.
For on a regular basis customers, the Daines textual content attracts its line across the asset a buyer pays with, at any buy dimension. A $5 espresso on a qualifying stablecoin would fall exterior gain-or-loss recognition, and the identical espresso on Bitcoin would keep within the capital-gains system.