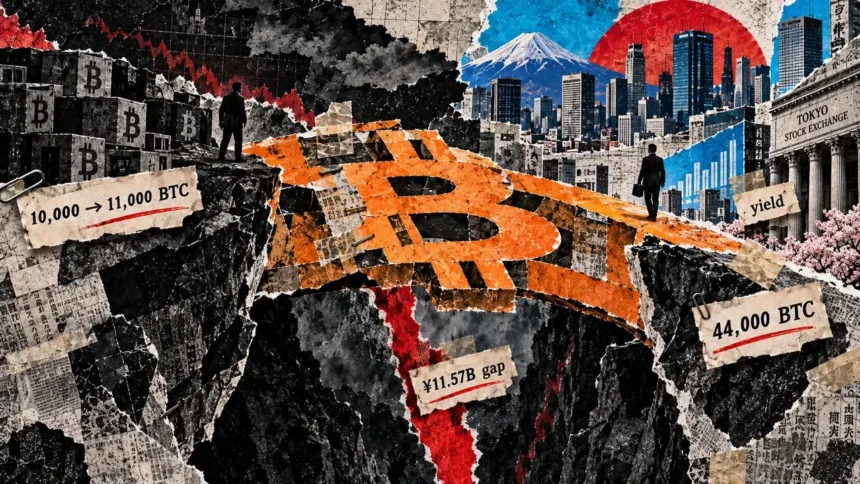
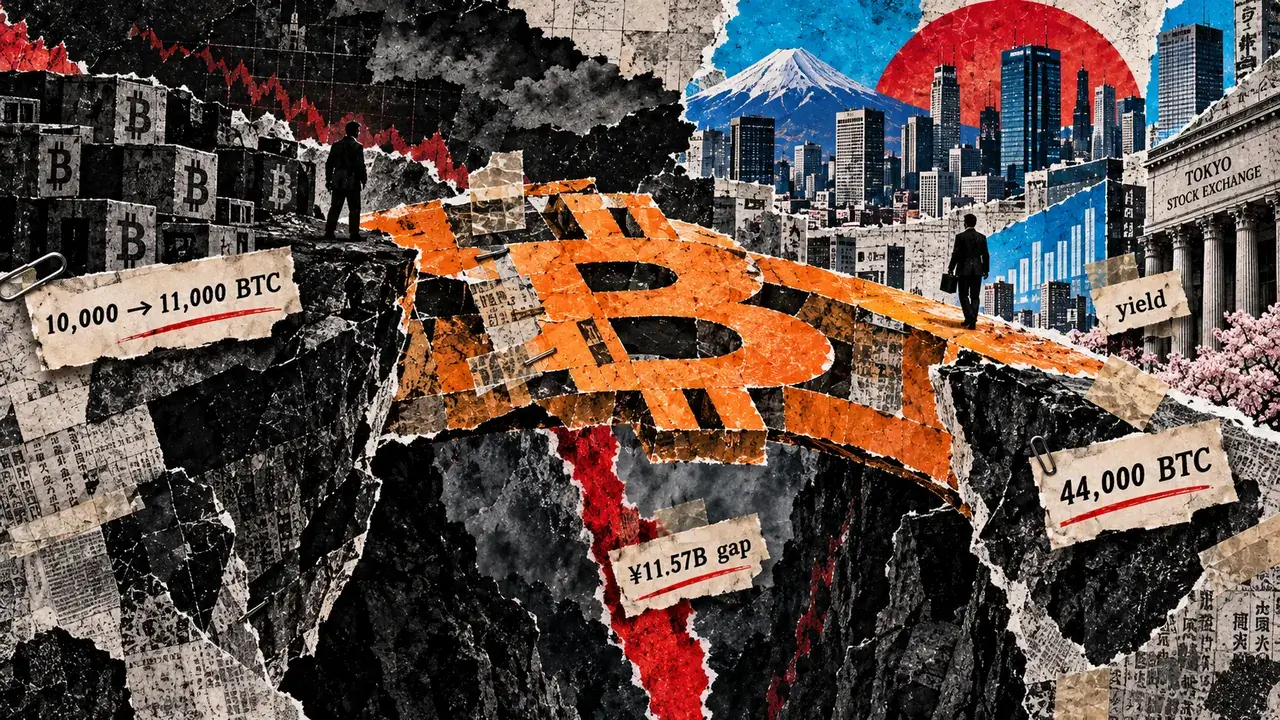
Metaplanet offered 10,000 Bitcoin and later purchased again 11,000 BTC to strengthen its credit score profile and develop past accumulation through the third quarter.
The Tokyo-listed firm mentioned it transformed sufficient Bitcoin into money through the third quarter to exceed the excellent principal of its bonds, borrowings, and different interest-bearing debt. It subsequently rebuilt the place at a better Bitcoin value, ending Sept. 30 with 44,000 BTC, up a internet 1,000 for the quarter.
The transaction types a part of a broader try to persuade score businesses and fixed-income traders that Metaplanet’s Bitcoin reserves may be monetized when obligations come due.
The corporate plans to hunt a credit standing and use a stronger financing profile to assist a brand new enterprise that borrows by bonds, most popular inventory and Bitcoin-backed amenities earlier than investing in higher-yielding belongings.
The liquidity demonstration got here at a value
Bitcoin rose between Metaplanet’s sale and repurchase, leaving the corporate paying considerably extra to rebuild the place it had offered.
In keeping with the preliminary, unaudited figures in its assertion, Metaplanet disposed of 10,000 BTC at a mean value of ¥12.47 million per coin, producing ¥124.7 billion in proceeds. It later bought 11,000 BTC at a mean value of ¥13.63 million per coin, spending ¥149.9 billion.
The roughly ¥1.16 million distinction between the sale and repurchase costs implies an opposed value differential of about ¥11.57 billion on the ten,000 BTC wanted to interchange the unique place. Metaplanet mentioned the upper reacquisition value mirrored Bitcoin’s rise between the 2 transactions.
The corporate mentioned it performed the transactions individually moderately than as a simultaneous change. It first offered the Bitcoin, held the proceeds in money, and solely later repurchased the asset, a sequence supposed to reveal that its reserves might really be transformed into money moderately than merely pointing to Bitcoin’s market liquidity.
That distinction is central to Metaplanet’s push into credit score markets. The corporate mentioned score businesses and fixed-income traders can low cost Bitcoin’s liquidity worth if an issuer is unwilling to promote it when required. Metaplanet needs the Q3 transaction to point out collectors that its long-term accumulation technique doesn’t forestall administration from monetizing Bitcoin to satisfy monetary obligations.
The sale additionally produced a US capital-loss carryforward. Metaplanet estimates subsidiaries of its US holding firm might acknowledge a deferred tax asset of about $97 million, probably out there to offset future capital features. The estimate stays topic to closing procedures and auditor overview, and the corporate mentioned the asset could in the end be smaller or not acknowledged in any respect.
Metaplanet mentioned the tax remedy might offset some or all the impact of the hole between its sale and repurchase costs and transaction prices if it acknowledges the deferred tax asset.
Metaplanet needs to show cheaper funding into recurring revenue
The corporate plans to make use of any enchancment in credit score entry for greater than financing extra Bitcoin purchases.
Its newly introduced Internet Curiosity Earnings Technique plans to boost capital by devices together with perpetual most popular inventory, company bonds often called BitBonds and Bitcoin-collateralized credit score amenities. Metaplanet would deploy that cash into belongings carrying yields above its all-in financing prices, retaining the distinction as internet curiosity revenue.
The corporate expects most popular securities issued by Bitcoin treasury corporations and related issuers to be amongst its principal funding targets. These investments will sit inside a strategic allocation that Metaplanet expects to signify about 10% to fifteen% of complete belongings, with Bitcoin remaining about 85% to 90%.
That may transfer Metaplanet nearer to a monetary middleman contained in the rising Bitcoin treasury market. Slightly than relying predominantly on rising Bitcoin holdings and fairness issuance, the corporate needs to boost cash at one value, make investments it at a better yield, and recycle the ensuing money circulate into debt service, most popular dividends, and additional Bitcoin purchases.
Metaplanet sees Japan as one potential supply of that funding benefit. It mentioned yen-denominated financing usually carries decrease rates of interest than greenback funding, whereas Metaplanet Securities offers it direct distribution to Japanese traders searching for Bitcoin-linked yield merchandise.
The corporate additionally expects its pending funding in Tremendous League Enterprise to develop its entry to US capital markets, probably permitting it to decide on between jurisdictions, maturities and financing buildings relying on market circumstances. The transaction has not but closed and stays topic to circumstances together with regulatory procedures and shareholder approval.
Metaplanet’s new revenue technique retains Bitcoin danger shut
Metaplanet’s try to diversify its earnings base might nonetheless depart a lot of the stability sheet uncovered to the identical underlying asset.
The corporate acknowledges that securities issued by Bitcoin treasury corporations could transfer with Bitcoin, creating correlation between its core reserves and a few investments supposed to supply recurring revenue. Metaplanet mentioned credit score, issuer focus, foreign money and leverage dangers will likely be managed inside limits authorized by its board.
Its revised capital coverage additionally distinguishes between borrowing used to amass Bitcoin and leverage used for strategic investments. Bitcoin-related borrowings are usually focused beneath about 10% of BTC internet asset worth, whereas financing connected to the strategic funding portfolio will likely be managed individually beneath an asset-liability framework.
Metaplanet expects the brand new internet curiosity revenue technique to have an immaterial impact on its 2026 consolidated outcomes, leaving the credit-rating effort and future financing phrases because the extra rapid exams. The corporate has cautioned that it has no assurance it is going to obtain a score, what stage it could obtain, or whether or not it might situation future bonds and most popular shares on the phrases it needs.
The following section will subsequently rely on whether or not collectors reward Metaplanet for proving it’s keen to promote Bitcoin when obligatory. A decrease value of capital would give the corporate room to scale its unfold technique; with out it, the economics of borrowing to purchase yield-bearing Bitcoin-linked securities turn into significantly tighter.