Metaplanet offered 10,000 BTC and acquired again 11,000 at the next common worth to indicate it was keen to promote its Bitcoin.
The Japanese treasury firm was pursuing a credit standing and higher entry to financing, and its Oct. 5 disclosure defined why turning cash into money was a part of that effort. Potential collectors wanted confidence that administration might use its holdings to fulfill obligations, even when shareholders purchased into the corporate due to these holdings.
Proving the purpose was costly, with Metaplanet receiving ¥124.7 billion from the sale and spending ¥149.9 billion on the next buy, paying roughly 9.3% extra per coin.
Making use of that common buy worth to the ten,000 cash changed produces a worth distinction of about ¥11.57 billion, earlier than transaction prices and potential tax results. That provides shareholders an costly receipt for the demonstration.
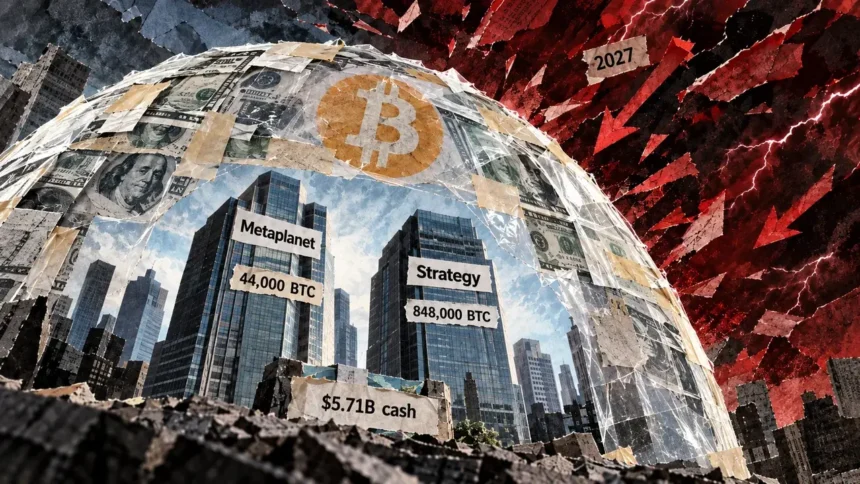
The corporate did not use the proceeds to repay borrowings or bonds, and it ended September with 44,000 BTC. Promoting was a part of an effort to enhance the financing behind continued accumulation.
That brings us to the unusual relationship underlying the company Bitcoin commerce. Shareholders are normally completely satisfied to attend years for the next worth, however lenders have contracts that specify when they need their a reimbursement. The identical reserve has to fulfill each teams.
Lenders would love their a reimbursement in {dollars}
An organization that owns an asset as liquid as Bitcoin is not fairly the identical as an organization having money obtainable to pay a invoice. Cash could also be pledged towards borrowing, or administration could also be unwilling to promote on the obtainable worth.
Both approach, collectors have to know what occurs when the fee date and the popular promoting worth do not cooperate.
Metaplanet’s June monetary assertion reported ¥67.49 billion in short-term borrowings and ¥8 billion in bonds payable inside a yr, towards ¥1.09 billion in money and deposits and ¥250 million in USDC.
The numbers exclude the corporate’s a lot bigger Bitcoin reserve and the financing it might entry, so the hole explains why lenders need greater than a coin depend when assessing compensation.
The contracts give dates to that dialogue, though the numbers under come from completely different reporting durations and should not be learn as a like-for-like comparability of present liquidity.
| Financing element | Metaplanet | Technique |
|---|---|---|
| Disclosed Bitcoin holdings | 44,000 BTC at Sept. 30 | 848,000 BTC at Oct. 4 |
| Money info | June 30: ¥1.09 billion in money and deposits, plus ¥250 million in USDC; a comparable September stability is not established right here | Oct. 4: $4.88 billion devoted reserve, plus $833.4 million in separate USD money |
| Recognized 2027 compensation provision | ¥8 billion zero-coupon bond issued with an April 23, 2027 redemption date and an early-redemption proper | Holders of $1.01 billion in notes can request money repurchase on Sept. 15, 2027 |
| Qualification | Full ¥8 billion was reported in June; the stability nonetheless excellent wants affirmation | Principal is predicated on June balances; fee will depend on train of the holder proper and intervening financing exercise |
Sources: Metaplanet’s bond phrases, June accounts, and October disclosure; Technique’s June submitting and October replace.
Technique’s notes technically mature in September 2028, however the holder’s proper to demand compensation brings a possible money obligation ahead by a yr.
Its June submitting additionally lists roughly $4.9 billion of notes with comparable holder repurchase rights throughout 2028, taking the principal related to these 2027 and 2028 dates to about $5.91 billion.
Holders should train their rights, and conversions or repurchases might cut back these quantities earlier than then, that means the corporate has clear factors when entry to money is extra necessary than confidence in Bitcoin’s eventual worth.
For this reason company Bitcoin has financing deadlines despite the fact that Bitcoin itself does not expire. Administration can borrow once more, challenge securities, or use money to fulfill obligations, however these choices have their very own prices, and so they aren’t equally enticing in each market.
Holding Bitcoin takes cash that is not Bitcoin
Technique has constructed a large greenback cushion, giving it extra room. Its Oct. 5 submitting reported a $4.88 billion devoted reserve and one other $833.4 million in separate dollar-denominated money, totaling roughly $5.71 billion as of Oct. 4.
The devoted reserve helps preferred-stock dividends and debt curiosity, and its coverage requires board authorization for different makes use of. The separate money stability gives a number of flexibility, so including the 2 collectively does not make the complete sum an unrestricted pot for future debt repayments.
The identical submitting exhibits how a lot work now goes into managing the cash’ financing. Between Sept. 28 and Oct. 4, Technique used $142.5 million from its reserve for dividends and curiosity, spent $154.1 million on repurchasing most well-liked shares, and acquired $13 million of Bitcoin.
Technique nonetheless held 848,000 BTC, purchased for about $63.97 billion, so Bitcoin dominates the stability sheet. However the money provides administration respiratory room when funds come due, serving to it keep away from promoting cash just because the market has chosen an inconvenient week to fall.
Its earlier Bitcoin gross sales and reserve-building already confirmed that supporting the securities financing the reserve might take priority over shopping for extra cash. Holding some cash in {dollars} may help the corporate retain Bitcoin by means of a downturn.
There’s additionally a shareholder model of the identical downside. When a treasury firm’s shares commerce above the worth of the property behind them, issuing shares can herald sufficient cash to extend Bitcoin publicity per present share.
When that premium disappears, the corporate should give away extra possession to boost the identical quantity, making the deal much less enticing to present traders.
Metaplanet’s June outcomes mentioned its market-value-to-net-asset-value measure (mNAV) was under 1.0 for a lot of the interval. Its coverage typically avoids discretionary common-share issuance under that threshold, so the restriction prevented some fundraising, leaving financing under earlier expectations.
The corporate continued shopping for by means of different funding sources, however the expertise demonstrates how dilution can complicate accumulation properly earlier than anybody faces a pressured sale. The reserve can get greater whereas an present shareholder’s financial curiosity turns into much less enticing.
Promoting some Bitcoin will be the higher choice when the choice is issuing shares cheaply. Most popular shares are a method to try this, however they offer traders claims forward of frequent shareholders, with the precise fee rights relying on the phrases.
Lacking a most well-liked dividend is not robotically a bond default, though disappointing these traders could make the subsequent fundraising tougher.
The choice is about how a lot Bitcoin shareholders can afford to maintain uncovered as soon as everybody financing the corporate has been accounted for, a much less photogenic quantity than whole BTC holdings.
One Bitcoin firm begins financing one other
Metaplanet can also be making an attempt to generate earnings past holding cash, as a result of Bitcoin by itself does not produce the {dollars} or yen wanted to service financing. Its revised allocation coverage targets roughly 85% to 90% of property in Bitcoin and 10% to fifteen% in strategic investments, together with income-producing securities.
Its Web Curiosity Earnings Technique seeks to earn extra from these investments than it pays to finance them. Doable investments embrace most well-liked securities issued by different Bitcoin treasury corporations, that means one firm’s plan to assist its Bitcoin reserve might embrace gathering funds from one other firm going through an identical problem.
That might present recurring money for financing prices or additional purchases, but it surely additionally creates the opportunity of publicity to the identical weak point twice. Falling Bitcoin costs might cut back Metaplanet’s core asset worth, whereas securities issued by different treasury corporations might lose worth or develop into much less reliable earnings sources.
The coverage acknowledges potential correlation, and the precise danger will depend on what the corporate buys and the way it funds these investments. It exhibits how far the enterprise can journey from the straightforward proposition of shopping for shares in an organization that owns Bitcoin.
Throughout the remainder of the market, these financing preparations make company purchases much less everlasting than the buildup bulletins could make them really feel. Firms can maintain believing in Bitcoin whereas slowing purchases, constructing money, or promoting cash as a result of the phrases obtainable to their shareholders have deteriorated.
Voluntary gross sales and compelled liquidations are completely different occasions, and neither firm’s disclosures set up an imminent liquidation. The extra fast consequence could be a purchaser spending its subsequent greenback on financing obligations.
Metaplanet’s spherical journey nonetheless has to earn its maintain by means of higher credit score entry or borrowing phrases, for the reason that disclosure does not show a score company ordered the sale or that cheaper financing has been secured.
Technique’s money cushion buys flexibility, however how a lot will depend on the obligations it must cowl and the capital it will possibly increase later.
Each instances make the identical level about holding Bitcoin by means of a company stability sheet: holding the cash requires selections in regards to the cash round them.
Administration keen to promote some Bitcoin on wise phrases could do extra for shareholders than administration defending a never-sell promise by borrowing expensively or handing away an excessive amount of possession to maintain it.