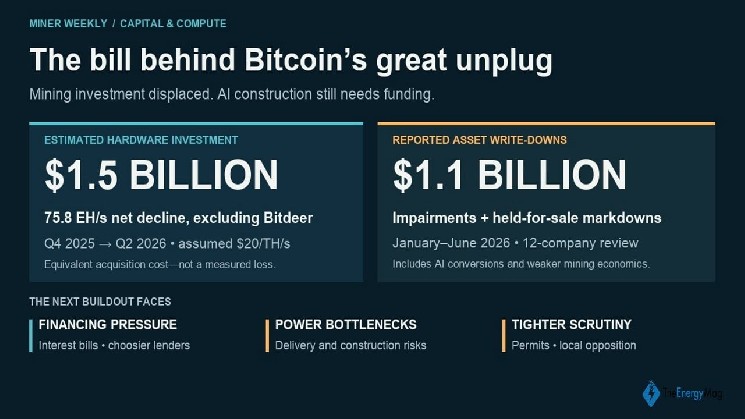
At $20 per TH/s, 75 EH/s corresponds to $1.5 billion of mining machines. That excludes the buildings, electrical tools, cooling and set up wanted to function them.
That’s an often-overlooked value of the AI transition: traders had already financed the mining capability being displaced. At some websites, tools was marked down inside months of beginning manufacturing, elevating questions on how a lot of that funding mining might get well earlier than AI took over.
And the accounting penalties have gotten seen.
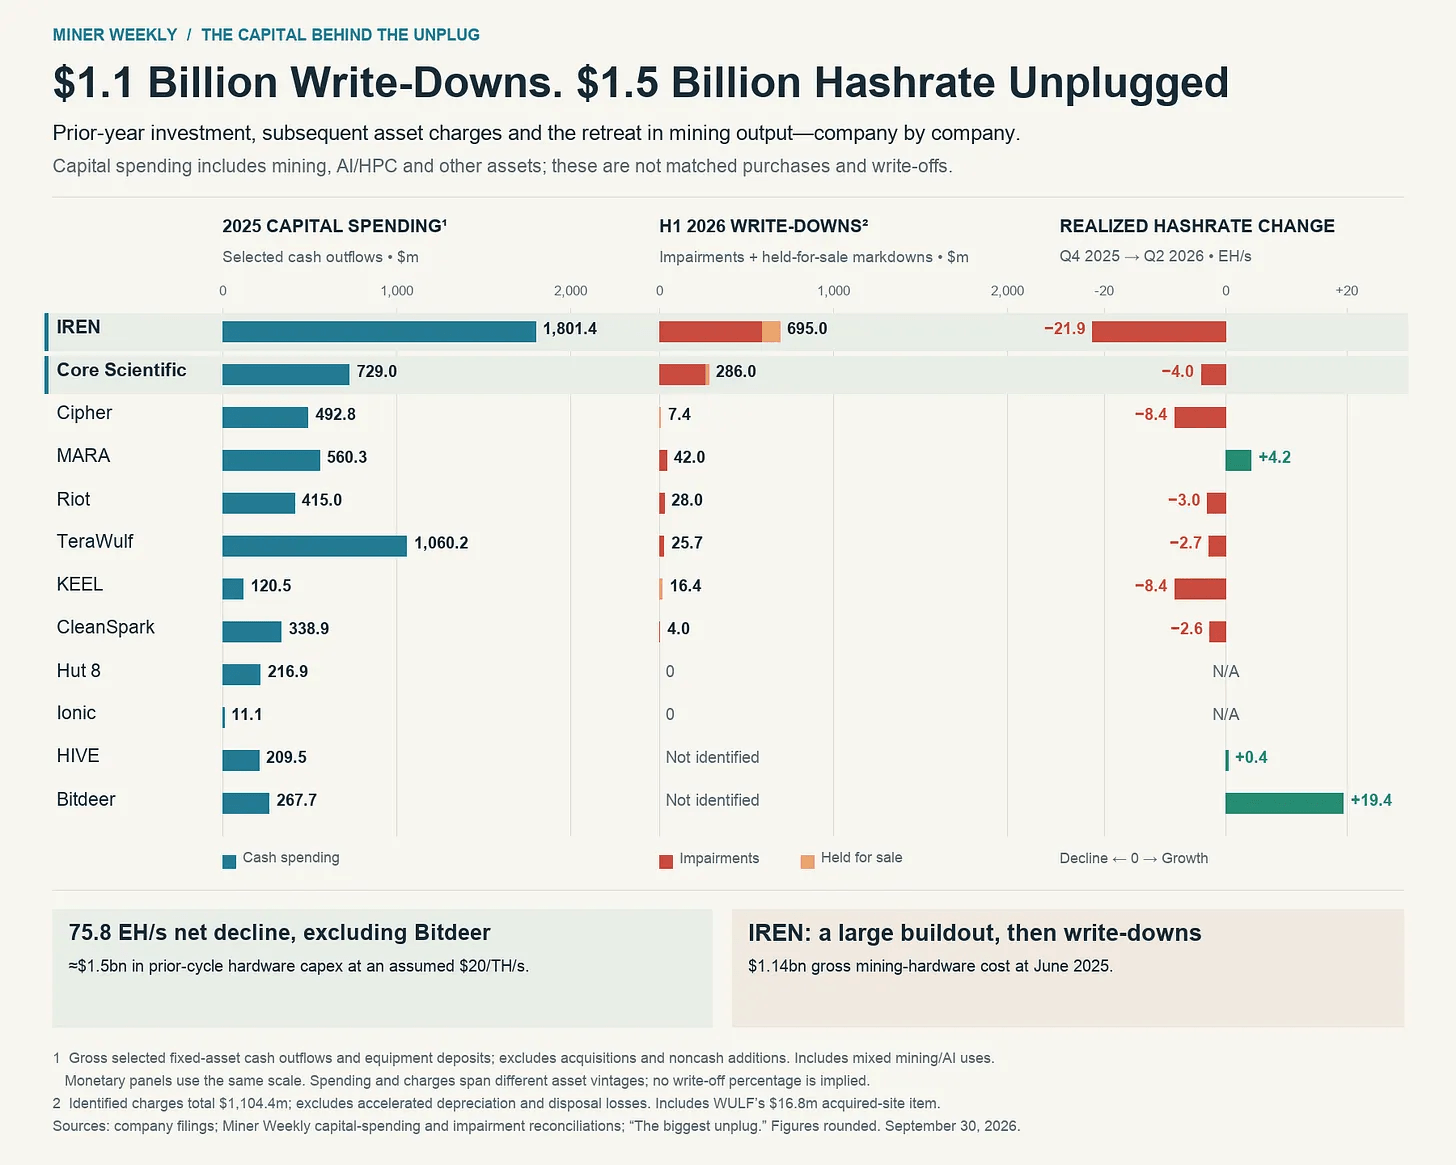
A separate assessment by TheEnergyMag of 12 tracked corporations recognized roughly $1.1 billion in asset impairments and held-for-sale markdowns throughout the first half of 2026. IREN and Core Scientific (NASDAQ: CORZ) accounted for nearly 89% of the entire.
The similarity between the 2 billion-dollar figures could appear coincidental. One estimates {hardware} funding equal to a discount in mining output; the opposite measures disclosed accounting fees throughout completely different belongings and corporations.
However each level towards the identical funding query: how a lot worth stays within the mining buildout as operators redirect their websites towards one other enterprise?
The spending surge was current. A March 2025 Miner Weekly challenge reported practically $5 billion in tools and infrastructure spending throughout the previous reporting cycle. Firms that individually disclosed mining-hardware purchases accounted for greater than $3 billion in 2024 alone.
That growth helped push Bitcoin’s community into zetahash territory in 2025. Operators purchased extra environment friendly machines and added capability to defend their share of manufacturing, whereas their opponents did the identical.
Now, a few of these investments are being displaced a lot earlier than the size of the spending may recommend.
Cipher’s Black Pearl facility started mining in mid-2025. By year-end, following an settlement to transform the positioning to high-performance computing, Cipher had recorded a $96.1 million markdown particularly on Black Pearl’s mining machines. Those self same machines generated $57.9 million in income throughout 2025—that means the markdown exceeded the positioning’s income from its first a number of months of operation.
That comparability doesn’t set up the challenge’s lifetime return, however it captures the compressed timetable. A newly working mine was already getting ready for a special objective. Cipher’s cost additionally occurred earlier than the first-half 2026 write-down whole.
IREN illustrates the size. It reached 50 EH/s in June 2025, then recorded roughly $695 million in impairments and held-for-sale markdowns throughout January–June 2026, with substantial fees related to mining belongings displaced by AI conversions.
Not each cost is an AI conversion value. Core Scientific attributed its main mining impairment to deteriorating mining economics. The broader whole contains different asset classes as nicely. The proof helps a expensive reassessment of mining funding, moderately than a declare that each greenback was sacrificed for AI.
Curiosity arrives earlier than the income ramp
Whereas write-downs are noncash when acknowledged, building and curiosity funds proceed to devour money when alternative amenities are being accomplished.
TeraWulf (NASDAQ: WULF) generated roughly $53 million in HPC leasing income throughout the first half whereas paying $131 million in money curiosity throughout the corporate. Money reserves and different earnings additionally assist these obligations, so the comparability just isn’t a standalone measure of economic misery. It reveals the hole between the income ramp and the price of financing it.
Entry to the subsequent spherical of funding may additionally grow to be tougher. In keeping with an excerpt from The Info’s reporting on Thursday, Société Générale and SMBC have grow to be extra selective about knowledge heart financing, whereas MUFG can be stepping again.
That may add one other constraint for miners halfway via conversions: retiring mining capability reduces the outdated income stream, whereas finishing its alternative nonetheless requires capital. Extra selective lenders might imply more durable phrases, extra fairness funding or a slower buildout.
On the similar time, delays can lengthen that interval after mining income has already been lowered. Oracle just isn’t a miner, however the current information on Venture Jupiter presents a concrete instance of how energy constraints can attain the monetary preparations behind an AI campus.
The underlying setback is documented: New Mexico’s land commissioner once more rejected a request in July to route a part of the challenge’s natural-gas pipeline via state belief lands. Jupiter’s deliberate fuel-cell energy system relies on pure gasoline.
A delayed campus opening just isn’t established. What is obvious is that power supply threat has grow to be a query of contractual obligations and who pays whereas a challenge waits.
Communities are demanding extra management
That uncertainty sits inside a widening political debate over knowledge facilities’ electrical energy demand, water use and results on family payments. New York introduced a pause on state environmental permits for brand spanking new hyperscale initiatives. Massachusetts launched extra approval necessities, whereas Chicago’s mayor proposed a year-long moratorium.
Current mining websites could grow to be extra invaluable the place they provide usable energy entry. However conversions nonetheless have to fulfill technical necessities and procure relevant approvals.
The price of ready can be dealing with renewed interest-rate strain with the Federal Reserve elevating its benchmark vary by 1 / 4 level to three.75%–4%. Current fixed-rate debt retains its phrases, however new financing, floating-rate borrowing and refinancing face a much less forgiving backdrop.
AI could finally show the higher use of those websites, however the return on the AI transition will depend upon greater than the income produced by every transformed megawatt. It’ll additionally depend upon the worth recovered from the mining tools, the price of rebuilding the positioning, and the way lengthy lenders have to be paid earlier than the brand new capability begins incomes.