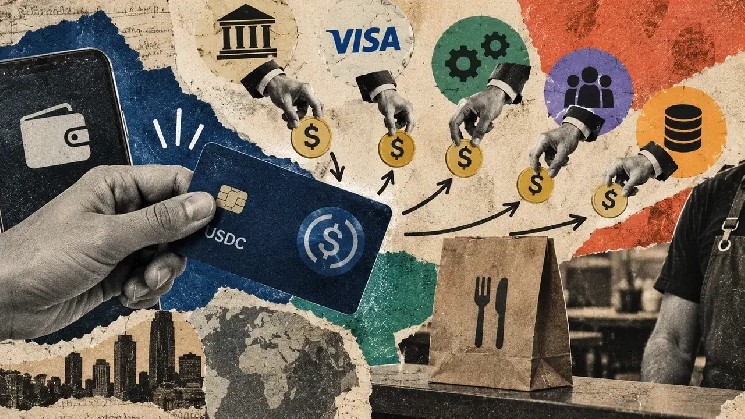
Bridge handles the conversion, so neither the restaurant nor its fee supplier wants to simply accept cryptocurrency, letting prospects spend stablecoins with out first withdrawing them to a checking account.
On Oct. 1, Visa reported greater than 160 stablecoin-linked card packages, with fee quantity up practically 200% from the earlier 12 months, making a rising enterprise for firms resembling Bridge, Wirex, and Rain that present the infrastructure behind these playing cards.
A lot of their income comes from fee charges, with extra alternatives in forex conversion, settlement financing, and buyer subscriptions. The brand new funding supply hasn’t eliminated the standard prices of operating a card program, which nonetheless must be lined each time somebody makes a purchase order.
The cardboard nonetheless runs on acquainted charges
The title printed on a stablecoin card not often identifies each firm concerned in processing the fee.
The patron app manages the client relationship, the regulated issuer gives the cardboard, the fee community connects collaborating establishments, and the product owner’s supplier handles acceptance, with conversion or settlement providers generally provided by one other enterprise.
These duties can overlap, however funding the acquisition with $USDC does not get rid of them, and every participant wants sufficient income to cowl its a part of the transaction.
Firms can carry out multiple function, and these aren’t separate charges essentially charged on each transaction.
Interchange issues as a result of the product owner’s financial institution or fee supplier pays it to the cardboard issuer, normally as a part of the broader charges retailers pay to simply accept playing cards.
Visa earns cash from its community and associated providers, whereas the issuer’s agreements decide how a lot income it could actually share with the corporate working the customer-facing card.
Bridge, which Stripe acquired in 2025, advertises a card product that enables program operators to retain 100% of interchange and cost extra transaction charges.
That offers crypto wallets and monetary apps a solution to earn cash when prospects spend their balances, though the quantity retained after processing prices, fraud prevention, compliance, and different bills is determined by every program’s preparations.
These bills do not finish when a fee is authorised. Disputed purchases can produce chargebacks weeks later, fraudulent transactions require investigation, and buyer assist prices proceed no matter whether or not the supplier earns sufficient from a person buy to cowl them.
Pavel Matveev, Wirex co-founder and CEO, advised CryptoSlate that packages utilizing the corporate’s infrastructure course of greater than $200 million in month-to-month spending, together with associate exercise.
The corporate hasn’t offered the requested breakdown of transaction charges and income sharing, so its reported processing quantity cannot set up how a lot of it Wirex retains.
Somebody has to fund the stablecoin fee
Card funds additionally create obligations that are not at all times settled when a buyer faucets the terminal. Authorization lets the service provider settle for the acquisition, whereas the monetary establishments concerned should later settle what they owe each other, generally earlier than the client’s funds have accomplished their journey by the system.
Stablecoins can transfer across the clock, however card packages nonetheless want entry to cash when settlement obligations come due, which creates demand for short-term financing even when the underlying transaction begins with digital {dollars}.
Rain, a supplier of stablecoin-linked card infrastructure, makes use of a revolving credit score facility from Credit score Coop to fulfill its Visa settlement obligations. Underneath the association, Rain attracts on the power to fund funds, then directs incoming cardholder proceeds by good contracts that assist repay the borrowing and curiosity.
Credit score Coop earns revenue for supplying cash throughout the interval between fee and compensation, permitting Rain to assist transactions with out holding sufficient idle money to cowl each settlement obligation fully from its personal assets.
Borrowing $1 million at an annual fee of 10% would price roughly $274 for in the future, in contrast with about $68 for six hours. These aren’t Rain’s disclosed borrowing phrases, however they present why sooner settlement can scale back financing prices with out altering how a lot prospects spend.
Revolving credit score additionally lets the identical capital fund successive batches of funds as earlier advances are repaid, so cumulative processing quantity can far exceed the quantity borrowed at any given second.
Credit score Coop’s financing mannequin permits card operators to cowl Visa settlement obligations with borrowed stablecoins quite than tying up their very own money. Visa claims the association has lowered borrowing prices by as a lot as 30% for some members, though the underlying phrases and allocation of credit score threat stay undisclosed.
The potential profit is decrease funding prices for card operators, however no proof but exhibits these financial savings are being handed on to prospects by decrease charges.
Visa additionally helps $USDC settlement between collaborating monetary establishments, permitting stablecoins to maneuver additional by the fee system with out requiring the service provider to obtain them.
The forex a buyer spends, the forex establishments use to settle, and the cash in the end deposited into the product owner’s account can all be completely different.
Stablecoin cashback has to outlive the mathematics
Rewards introduce one other price, and the price revenue out there to cowl them may be a lot smaller than the marketed cashback fee.
Britain’s Fee Programs Regulator units interchange caps of 0.2% for lined home shopper debit transactions and 0.3% for lined shopper credit score transactions. On a qualifying £100 debit buy, that leaves at most 20 pence in interchange earlier than the issuer’s working bills or any share paid to a card associate.
Providing 2% cashback on the identical buy would price £2, leaving a £1.80 hole that would want to return from one other income supply or a promotional funds.
The UK caps do not apply to each stablecoin card or worldwide transaction, however they present why beneficiant rewards cannot at all times be funded from unusual fee charges. Suppliers can cowl the distinction by subscriptions, conversion prices, revenue from different providers, or subsidies designed to draw new prospects.
These preparations develop into extra essential when the marketed cashback is determined by sustaining a qualifying token stability, becoming a member of a paid plan, or assembly minimal spending necessities.
With the Wirex card, increased cryptoback charges are tied to subscription tiers and token lockups, and rewards fluctuate by market and buyer plan.
The client’s return is determined by all the association. Cashback loses a lot of its attraction when a month-to-month subscription, conversion unfold, or foreign-transaction cost eats into the profit, particularly for purchasers who do not spend sufficient to justify an upgraded plan.
For the operator, a buyer who makes one buy to gather an introductory bonus has completely different economics than somebody who makes use of the cardboard for groceries, journey, and payments each month.
Income from repeat spending can assist cowl the price of buying and supporting prospects, however that is determined by how a lot this system earns after rewards and its companions’ charges.
The client could get monetary savings, however not at all times
Stablecoin playing cards supply their greatest benefit to individuals who already obtain or maintain digital {dollars}.
For instance, freelancers paid in stablecoins can spend their earnings with out repeatedly transferring cash by a crypto trade and an area financial institution, avoiding a few of the steps and prices concerned in accessing these funds.
Whether or not that comfort interprets into financial savings is determined by the client’s alternate options and the transaction’s complete price.
Somebody incomes and spending euros faces a distinct calculation as a result of changing euros into greenback stablecoins after which again into euros at checkout can introduce forex prices that would not come up with an unusual euro-denominated financial institution card.
Even somebody paid straight in stablecoins wants to think about conversion spreads, card charges, and the trade fee utilized when spending in native forex.
Greenback-linked tokens purpose to take care of a steady worth in opposition to the greenback. Their buying energy in euros, pesos, or kilos can change with foreign-exchange charges, no matter whether or not the token maintains its greenback peg.
These variations make it exhausting to estimate typical buyer financial savings from card-spending totals alone. Wirex hasn’t provided transaction-level price figures or retention information that will let its reported fee exercise connect with particular person buyer economics, whereas public spending dashboards do not present how a lot of every buy stays with the businesses working the playing cards.
Regardless of the speedy development in stablecoin-card spending, the amount transferring by these merchandise does not set up whether or not prospects maintain utilizing them after introductory incentives finish or whether or not suppliers persistently earn greater than they spend serving these prospects.
Stablecoin playing cards made digital {dollars} simpler to make use of at unusual companies with out asking retailers to alter how they settle for funds. The businesses making that attainable now earn cash from the identical providers which have supported card funds for many years, with blockchain-based settlement probably decreasing some prices.
For individuals paying with stablecoins, the profit comes all the way down to the cash left after each price, conversion, and reward is counted. For the businesses behind the playing cards, it comes down as to if sufficient prospects discover that profit value returning for.