Luxor, a Bitcoin mining derivatives supplier, reported a 6–13% annualized Bitcoin financing unfold in its September lookback, revealed Oct. 9. It says lenders and Bitcoin treasury corporations purchased pay as you go mining energy and paired it with a worth hedge, whereas miners used the reverse commerce to acquire financing.
The return comes from the low cost a miner accepts for receiving cash upfront. The hedge can repair gross BTC receipts if mining supply and settlement carry out, whereas the investor’s capital stays uncovered to failure in that reimbursement chain. Luxor’s reported September vary doesn’t set up an executed return after prices or a quote obtainable in the present day.
The place the Bitcoin return comes from
Mining energy, or hashrate, produces income at a fee referred to as hashprice. Luxor’s contracts specific that fee in Bitcoin or {dollars} per unit of computing energy per day. Shopping for future mining energy provides the purchaser publicity to the revenue that energy generates over the contract interval.
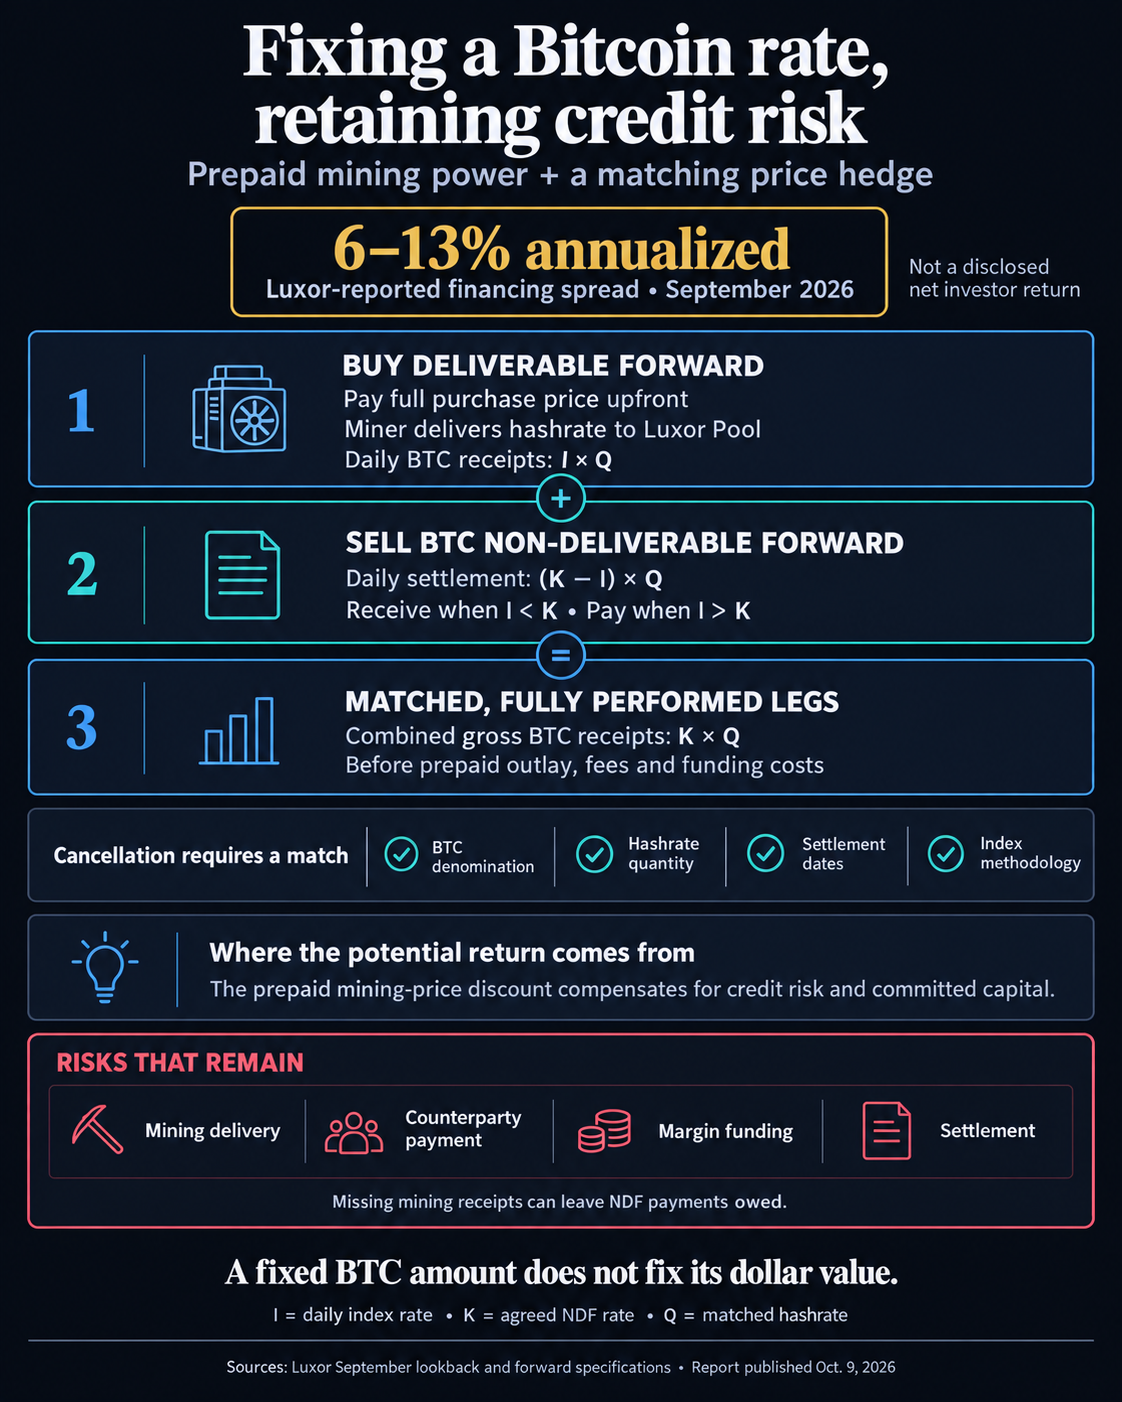
In a deliverable ahead, the customer pays the complete buy worth upfront. The vendor should ship hashrate to Luxor’s Bitcoin Mining Pool, with the customer’s each day BTC settlement tied to the hashprice index and contracted quantity of mining energy.
That prepayment provides financing to the miner. Luxor says deliverable forwards sometimes commerce under comparable non-deliverable forwards to compensate the customer for credit score threat and the price of committing capital. The decrease pay as you go buy worth is the supply of the lender’s potential revenue.
And not using a hedge, the customer’s receipts would fluctuate with the mining-revenue fee. The paired commerce provides a sale of a non-deliverable ahead, or NDF, which settles in money fairly than requiring bodily mining-power supply.
For the NDF vendor, each day settlement is the agreed hashprice minus that day’s index fee, multiplied by the contracted hashrate. When the index is under the agreed worth, the vendor receives the distinction. When it’s above, the vendor owes the distinction.
If the 2 legs use the identical BTC denomination, hashrate amount, settlement dates and index methodology, their worth exposures cancel. Totally delivered mining receipts on the each day index fee, plus the NDF settlement, equal receipts on the fastened NDF fee. The revenue is determined by how a lot these receipts exceed the pay as you go buy price and different prices.
The matching circumstances matter. A hedge overlaying completely different portions or dates leaves a part of the mining income uncovered. A dollar-denominated contract additionally can’t merely be substituted for a BTC-denominated one whereas preserving the identical Bitcoin payoff.
A BTC-denominated hedge additionally leaves the greenback worth of Bitcoin receipts uncovered to BTC/USD adjustments.
Luxor’s product pages describe month-to-month contracts as much as 18 months out and customized durations. That’s the common product vary; the September financing dialogue doesn’t establish which tenors produced the reported 6–13%, or give its annualization method.
Annualized pricing additionally doesn’t imply an investor earns the quoted share over any shorter contract. The precise contract interval, reimbursement timing, prices and capital dedicated throughout each legs decide the return on the investor’s funds.
Supply failure can go away the hedge operating
The cancellation works as a result of the customer receives the mining income towards which the NDF settles. If promised mining energy just isn’t delivered and the shortfall just isn’t cured, that income leg could be smaller than anticipated whereas the hedge nonetheless has settlement obligations.
When settlement hashprice exceeds the NDF’s fastened fee, the vendor owes the distinction, anticipating greater mining receipts to offset it. If these receipts fail to reach, the worth hedge can require cost with out the corresponding revenue.
There may be additionally a distinction between the miner supplying the output and the investor’s contractual counterparty. Luxor’s order-book documentation says Luxor is counterparty to each the customer and vendor. The platform shows purchase and promote orders, and its derivatives workforce contacts the events to substantiate trades; the e book itself just isn’t an execution system.
For an investor, that makes Luxor’s personal efficiency a part of the reimbursement chain alongside the mining operation.
Luxor’s upfront-payment procedures require vendor credit score profiling earlier than cash is superior. The necessities cowl mining-site and energy paperwork, insurance coverage, pool efficiency, monetary statements and future obligations. Its margin coverage additionally lists documentation for a efficiency bond or guarantor amongst its supplemental checks.
Credit score checks scale back uncertainty a couple of vendor’s skill to carry out, whereas restoration after failure is determined by enforceable claims. The general public necessities don’t specify a whole reimbursement precedence or establish which property an investor might implement towards after default.
For eligible traders, collateral custody and the flexibility to exit stay a part of the credit score publicity. The order e book permits open orders to be canceled; that doesn’t set up an exit from a confirmed ahead.
Margin adjustments the capital calculation
Collateral determines how a lot further capital could also be wanted to keep up the hedge. Luxor’s margin coverage requires BTC collateral for BTC contracts and collects variation margin when the decrease of realized and unrealized margin balances falls under upkeep necessities. Credit score-qualified deliverable sellers can have customized procedures primarily based on realized balances.
The coverage describes preliminary margin as safety towards potential publicity in the course of the time wanted to shut out and exchange a defaulted place.
The general public schedules are usually not constant: the NDF web page quotes 18% BTC preliminary margin and the DF web page quotes 18% vendor hashprice margin plus potential supply margin, whereas the final coverage lists 17.5% BTC preliminary and 14% upkeep on non-offset future each day notional. The pages don’t clarify the distinction.
The coverage identifies Nov. 14, 2025, as its final initial-margin analysis. Certified BTC deliverable sellers can obtain discretionary preliminary phrases after supplemental credit score profiling, so neither product-page fee establishes a common requirement for the paired commerce.
Pay as you go DF patrons are exempt from that leg’s initial-margin schedule as a result of they already pay in full. That exemption doesn’t set up that their NDF leg is collateral-free.
That capital issues when evaluating the reported unfold with an investor’s internet return. Charges, execution costs and any further funds dedicated to help the hedge can have an effect on the quantity earned relative to the cash put in danger.
Luxor’s Steelhead Capital Administration case examine describes the pairing in follow: Steelhead purchased bodily hashrate upfront, added an NDF to repair hashprice, and used Luxor Pool for supply, reward distribution and settlement.
Luxor says each day reimbursement reduces publicity over the contract’s life. That helps the mechanism of returning funds progressively, whereas the remaining unpaid quantity nonetheless is determined by efficiency.
Entry can be restricted. Luxor’s sources web page says contributors should qualify as Eligible Contract Members. Its examples embrace entities with greater than $10 million in property and entities with a minimum of $1 million in internet price hedging business threat. The construction just isn’t universally obtainable to retail Bitcoin holders.