Japan’s October 6, 2026 public sale of ten-year authorities bonds attracted extra aggressive demand relative to the debt bought, whilst its common yield rose to three.101%. For Bitcoin, increased returns on Japanese debt increase a query about how a sustained shift in bond allocation may have an effect on international financing.
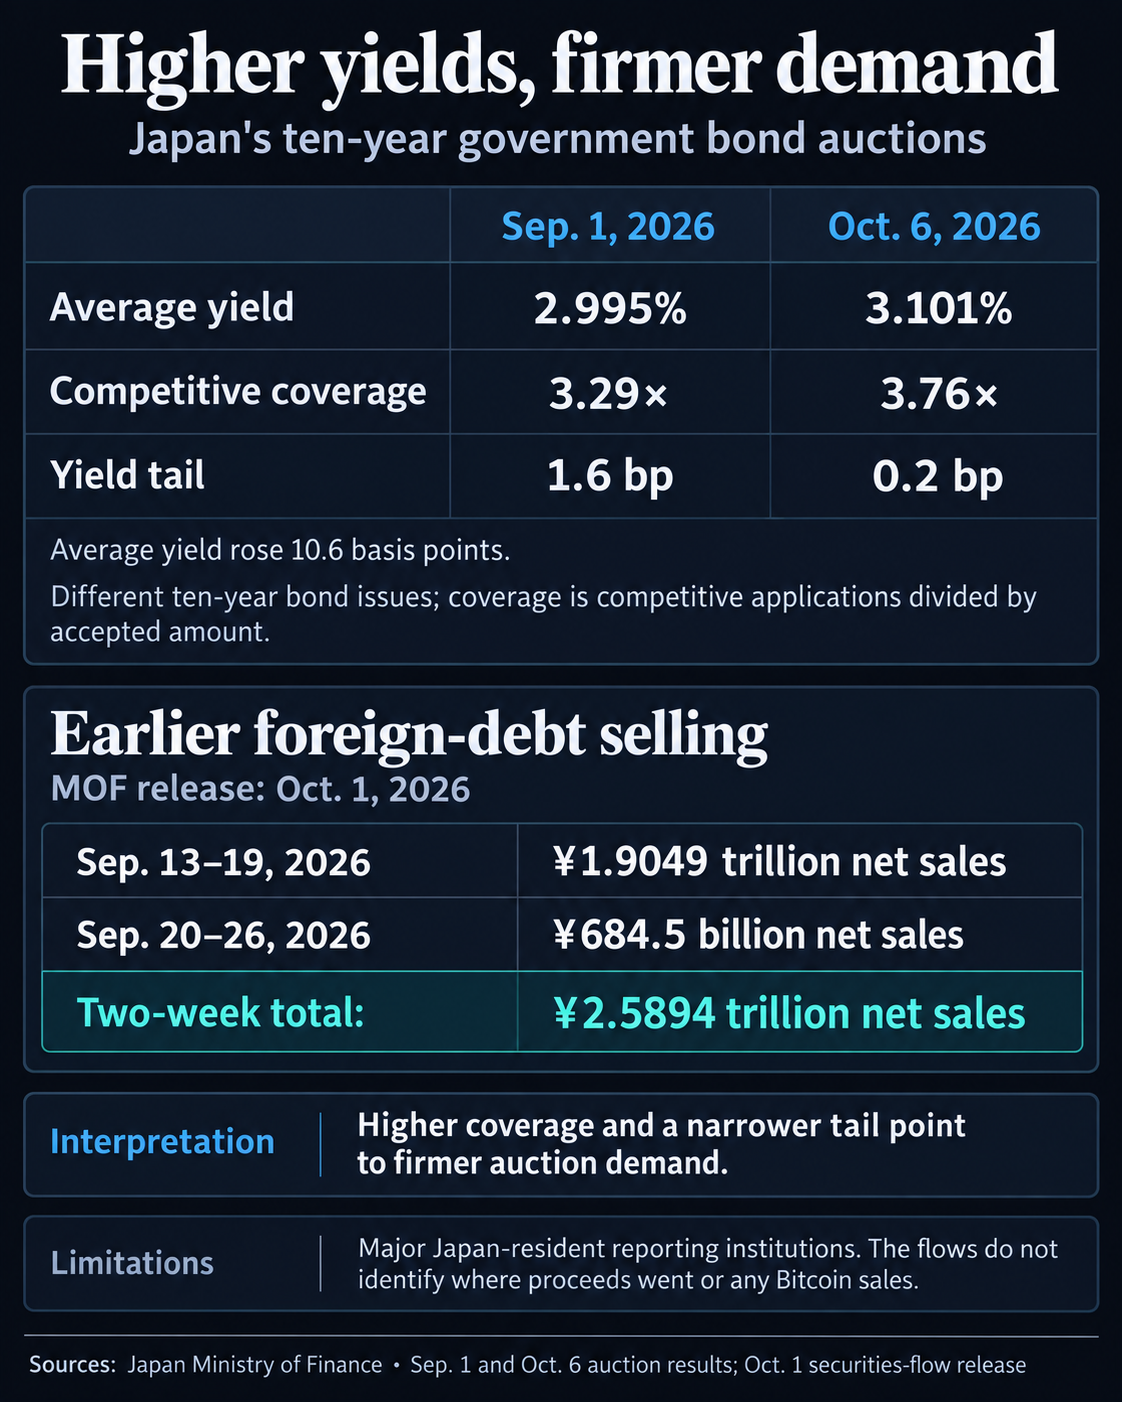
The Ministry of Finance’s consequence put the common yield up from 2.995% on the September 1 sale, a rise of 10.6 foundation factors. Aggressive public sale protection, the quantity sought by members divided by the quantity accepted, rose from about 3.29 instances to three.76 instances.
The yield tail narrowed from 1.6 to 0.2 foundation factors. That hole measures the yield on the lowest accepted value towards the common yield. Alongside the upper protection, the smaller tail factors to firmer demand on the increased yield.
The backdrop is 2 earlier weeks of foreign-debt promoting. MOF’s October 1 move launch recorded internet long-term debt gross sales of ¥1.9049 trillion throughout September 13–19 and ¥684.5 billion throughout September 20–26. Collectively, these weekly observations quantity to internet gross sales of ¥2.5894 trillion.
The sequence covers designated main Japan-resident reporting establishments and classifies international securities by issuer residence. It doesn’t establish US Treasury gross sales, foreign money conversion, reinvestment into Japanese authorities bonds or Bitcoin transactions.
The potential financing stress on Bitcoin
If Japanese establishments persistently favor home bonds over abroad debt, lowered international bond demand may increase borrowing prices and weigh on capital out there for risk-taking.
The authors of a Financial institution for Worldwide Settlements working paper establish international funding circumstances and speculative motives as necessary drivers of cross-border Bitcoin and Ether flows. Their 2017 to mid-2024 pattern helps the relevance of funding circumstances to crypto flows.
Institutional portfolio allocation additionally differs from leveraged yen carry trades, which contain positions financed with borrowed yen. A ten-year public sale yield doesn’t measure the short-term price of that borrowing. Of their August 2024 evaluation, BIS researchers described how deleveraging and margin will increase amplified that month’s market turbulence. It illustrates how financing stress can unfold throughout markets, with out demonstrating a present unwind.
The following helpful proof is whether or not foreign-debt promoting continues alongside independently noticed funding stress. That sample could be per the proposed Bitcoin financing channel; renewed shopping for and calm funding would weaken the interpretation.