When Circle’s Arc mainnet went reside final week, Jeremy Allaire known as it “the only most vital launch in Circle’s historical past since $USDC itself.” The brand new blockchain was constructed particularly for monetary markets, with $USDC used for gasoline and main TradFi firms together with Visa and Mastercard collaborating as validators.
They spend by way of playing cards, financial institution transfers and fee networks.
That’s the place Wirex thinks the following stablecoin battle will likely be fought. The corporate launched on Arc’s mainnet on day one and has built-in the community into its stablecoin funds infrastructure, together with Wirex One, its new onchain banking product.
Visa and Mastercard Validate Arc. That Doesn’t Robotically Put Stablecoins on Their Rails
Visa and Mastercard are each validators on Arc, serving to safe the blockchain. But being an Arc validator and permitting customers to truly spend stablecoins by way of Visa or Mastercard are two very completely different items of infrastructure.
Most stablecoin card packages shouldn’t have direct membership within the main card networks. As an alternative, they depend on a BIN sponsor or program supervisor, including one other middleman together with extra prices and settlement home windows.
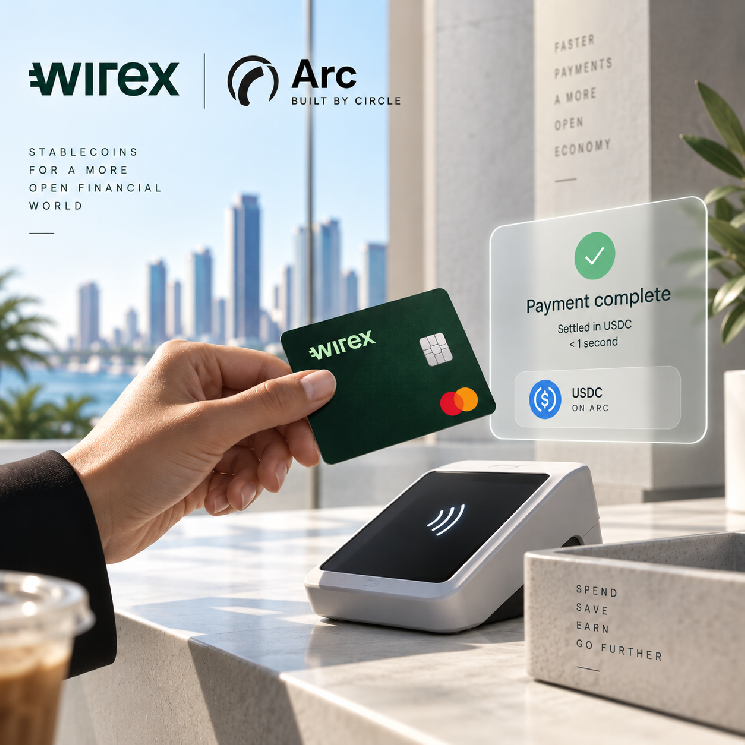
Wirex is uncommon as a result of it holds principal membership with each Visa and Mastercard and says it will possibly settle card transactions instantly in $USDC and EURC with out an middleman financial institution. Which means Arc’s sub-second settlement can probably journey additional by way of the fee stack relatively than instantly working into one other middleman’s timetable.
The excellence sounds technical, however the client expertise is straightforward to grasp. A stablecoin can transfer virtually immediately on a blockchain, however that pace issues a lot much less if changing it into one thing spendable nonetheless depends upon slower monetary infrastructure.
Wirex One Is Placing Arc in Entrance of Shoppers
Wirex has been testing on Arc since June and says greater than 20,000 customers participated within the closed beta for Wirex One earlier than its public launch. The product combines stablecoin-funded spending, transfers, yield and different monetary providers whereas utilizing Arc as a part of the underlying settlement infrastructure.
At launch, Wirex One features a stablecoin-funded card providing as much as 8% cashback in USD, chosen crypto and stablecoin yield merchandise, multi-currency accounts, fee-free FX and ATM withdrawals, and transfers by way of techniques together with SEPA, ACH and Quicker Funds. Wirex says tokenized equities and perpetuals are additionally scheduled to be added.
The goal market can also be completely different from the everyday crypto card pitch. Wirex is positioning the product towards the “mass prosperous”: prospects who could have outgrown fundamental retail banking however don’t meet the wealth thresholds related to conventional personal banking.
That may be a sizable market to chase. The personal banking sector is projected to develop by greater than 10% yearly to succeed in $1.24 trillion by 2035, in response to analysis cited by Wirex.
Stablecoin Banking Is Changing into a Greater Enterprise
Wirex’s Arc launch additionally sits inside a a lot bigger shift towards stablecoins turning into the infrastructure beneath on a regular basis monetary merchandise.
Wirex says its broader stablecoin banking infrastructure lately reached $2 billion in annualized card spending quantity. By way of the identical infrastructure, fintechs and wallets can launch accounts, playing cards, funds, payouts, yield and cashback merchandise whereas settling exercise in stablecoins.
The corporate has scale behind that pitch. Wirex says it has served greater than 8 million customers throughout 130 nations and processed greater than $20 billion in transactions since launching in 2014.
That makes Arc attention-grabbing for a purpose that goes past one other blockchain launch. Blockster coated Arc’s mainnet launch as Circle positioned the community round monetary markets, funds and stablecoin settlement. Wirex supplies an early take a look at of what occurs when these rails attain an precise client monetary product.
The Stablecoin Race Might Be Gained Above the Blockchain
Arc’s technical efficiency issues. So do its validators, privateness structure and $USDC-based gasoline mannequin. However none of these options robotically flip a stablecoin into one thing someone can use at a restaurant, store or ATM.
That requires one other layer connecting blockchain settlement with present fee networks.
Wirex’s argument is that this layer could in the end decide which stablecoin networks acquire real-world utilization. A blockchain can settle a transaction in lower than a second, however customers will decide the expertise by what occurs after they faucet a card, switch cash or attempt to entry their funds.
Arc is constructing quicker rails beneath digital {dollars}. Wirex is betting that the businesses connecting these rails to the monetary world individuals already use could also be simply as vital because the blockchain itself.