US spot Bitcoin ETFs recorded a $450 million web outflow on Sept. 15. It greater than erased the earlier session’s $159 million influx, whereas the six accomplished periods since Sept. 8 added as much as a web $753 million withdrawal.
The reversal eliminated the transient demand sign that appeared because the Federal Reserve started its two-day coverage assembly. Bitcoin traded close to $75,900 at press time, placing the market near the decrease finish of the vary in Glassnode’s newest weekly snapshot.
ETF web flows measure creations and redemptions throughout the funds. Investor identities and direct Bitcoin sale execution fall exterior the dataset. The helpful conclusion is narrower: the ETF reversal arrived alongside broader sell-side stress.
Spot and perpetual sellers transfer collectively
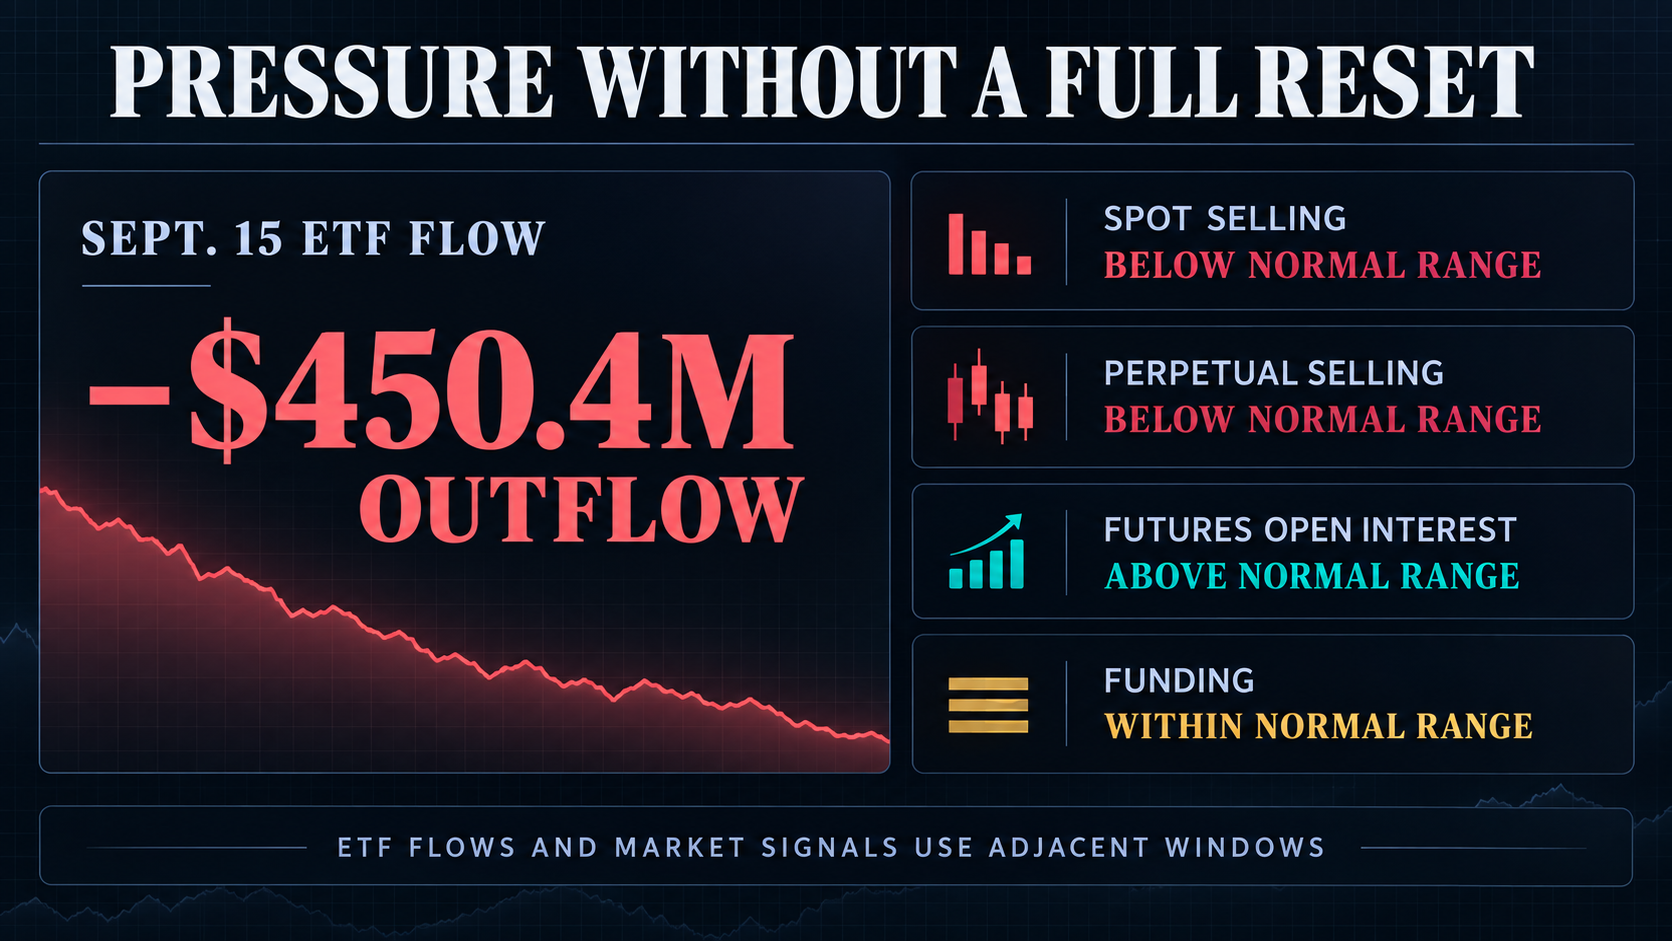
Glassnode’s Week 38 report confirmed spot cumulative quantity delta, a measure of aggressive shopping for minus aggressive promoting, at unfavourable $142 million. That was beneath its unfavourable $115 million decrease statistical band and indicated that sellers had been dominating exercise on the centralized exchanges in Glassnode’s dataset.
Derivatives sellers had been lively too. Perpetual cumulative quantity delta dropped to unfavourable $605 million, far beneath its unfavourable $233 million decrease band, signaling aggressive promoting in perpetual futures.
Leverage remained elevated regardless of the stress. Futures open curiosity, the worth of excellent contracts, eased from $37 billion to $36 billion however remained above its $36 billion higher band. Lengthy-side funding funds, which mirror the recurring switch between perpetual longs and shorts, rose to $1.4 million whereas staying inside their regular statistical vary.
The mixture leaves extra positioning accessible to amplify one other shock, whereas regular funding argues in opposition to an already excessive long-side imbalance. The Glassnode snapshot additionally predates Farside’s Sept. 15 ETF row. The adjoining home windows help a broad-pressure studying whereas leaving any causal hyperlink between ETF redemptions and change promoting unresolved.
The Federal Reserve’s coverage choice remained pending on the identical reporting cutoff. Bitcoin’s first post-decision check was due to this fact nonetheless forward.
A constructive response would pair value stabilization with enhancing spot move whereas open curiosity stays orderly. A extra convincing bearish second transfer would mix renewed spot promoting with a sharper fall in open curiosity and a funding reset, proof that the stress had unfold into pressured deleveraging.
Earlier than the choice, the market is finest described as susceptible slightly than damaged: spot distribution has deepened, derivatives sellers are lively, and positioning stays massive sufficient to enlarge the subsequent transfer.