Staking was speculated to strengthen Ethereum exchange-traded funds (ETFs), however BlackRock’s early outcomes present traders nonetheless favor its authentic fund.
When US spot Ethereum ETFs launched in July 2024, the absence of staking was broadly recognized as considered one of their largest structural disadvantages. Buyers shopping for the funds gained publicity to ETH’s value however forfeited the rewards obtainable to holders who dedicated their tokens to securing the Ethereum community.
On the time, JPMorgan cited the elimination of staking from ETF filings as one cause it anticipated weaker demand than for Bitcoin funds. BitMEX Analysis equally argued that institutional traders might discover non-staking merchandise much less enticing, whereas Galaxy Digital estimated that giving up staking represented a significant alternative value for ETF traders.
BlackRock now gives an early check of that argument.
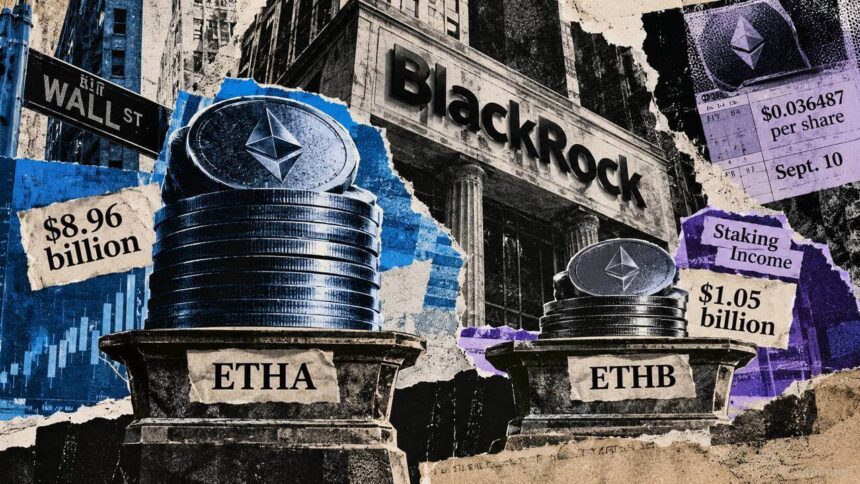
Its iShares Ethereum Belief ETF (ETHA) offers simple publicity to ether with out staking. The newer iShares Staked Ethereum Belief ETF (ETHB) stakes a part of its holdings and distributes a portion of the ensuing revenue to shareholders.
Thus far, including yield has not overturned the hierarchy.
ETHA held about $8.96 billion in internet property on Sept. 11, in contrast with roughly $1.05 billion for ETHB, BlackRock fund knowledge present.
The distinction is even bigger in secondary-market buying and selling: ETHA generated an estimated $1.86 billion of share turnover that day primarily based on quantity multiplied by its closing value, roughly 30 instances ETHB’s $61.8 million.
ETHB can also be paying traders. The fund listed a distribution of $0.036487 per share payable Sept. 10 after starting to earn staking rewards in Might.
But ETHA attracted $148.8 million of internet inflows on Sept. 11, in contrast with $18.3 million for ETHB, Farside Buyers knowledge present.
The comparability comes with an necessary limitation. ETHA has had considerably extra time to build up property, buying and selling relationships, and institutional adoption, whereas ETHB remains to be constructing its monitor document. Its roughly $1 billion asset base additionally represents significant demand for a more recent product.
Nonetheless, ETHA’s continued inflows after staking revenue grew to become obtainable problem the stronger model of the thesis that lacking yield was the primary constraint on Ethereum ETF demand.
Staking removes one handicap, however not ETHA’s head begin
ETHB removes a lot of the opportunity-cost downside that formed criticism of the unique Ethereum ETF construction. It can not instantly replicate the liquidity ETHA has collected since turning into one of many first US spot Ethereum ETFs.
BlackRock reported a 30-day median bid-ask unfold of 0.05% for ETHA as of Sept. 11, in contrast with 0.06% for ETHB. That distinction is small, however the a lot wider disparity in buying and selling exercise provides establishments considerably extra capability to enter and exit bigger ETHA positions.
Day by day flows have but to point out a sustained migration towards the staking product.
Each funds recorded no internet flows on Sept. 8 and attracted capital on Sept. 9. ETHA suffered an outflow on Sept. 10 whereas ETHB gained property, however each returned to inflows the subsequent day, with ETHA attracting considerably extra money.
These actions can not set up whether or not particular person traders are rotating between the merchandise. ETF circulate knowledge establish creations and redemptions on the fund degree however don’t reveal whether or not an investor promoting ETHA subsequently used the proceeds to buy ETHB.
That distinction issues if staking ultimately adjustments the aggressive stability. A sustained interval of ETHB creations accompanied by ETHA redemptions would offer a lot stronger proof that traders are actively exchanging easier publicity for yield-bearing publicity.
Yield introduces prices and one other layer of liquidity administration
Staking additionally provides ETHB a extra difficult financial construction than merely including yield to ETHA.
About 75.85% of ETHB’s ether was labeled as staked as of Sept. 10, whereas roughly 24.15% remained unstaked. The unstaked portion offers liquidity for fund operations and redemptions with out requiring BlackRock to attend for ether to exit Ethereum’s staking course of.
Buyers additionally face two separate layers of prices.
ETHB carries a normal annual sponsor payment of 0.25%, the identical headline price as ETHA, though a short lived waiver reduces the payment to 0.12% on its first $2.5 billion of property for 12 months starting March 12.
Staking rewards carry one other cost. An April prospectus complement units the mixture staking payment at 10% of gross staking consideration, down from an earlier 18%.
The charges apply to totally different bases. The sponsor payment is assessed towards fund property, whereas the staking payment is deducted from rewards generated by collaborating in Ethereum’s proof-of-stake community.
Distributions are additionally conditional, not a hard and fast yield. BlackRock can take into account staking consideration obtained, authorized necessities, and the fund’s operational and liquidity wants when figuring out funds.
The construction introduces extra redemption concerns. Beneath pressured circumstances, ETHB’s prospectus permits delayed settlement or cash-only redemptions when staking exit instances or obtainable liquidity make extraordinary settlement tougher.
These trade-offs put the staking thesis to a more durable check than whether or not traders like receiving extra revenue.
ETHB should generate sufficient after-fee worth to influence traders to decide on a youthful, less-traded car over an incumbent with practically $9 billion in property.
The following sign will likely be whether or not ETHB can convert its distribution function into sustained creations relatively than episodic demand round payouts. If that occurs whereas ETHA begins shedding property, the staking thesis may have stronger help.
Till then, BlackRock can seize each preferences: traders prioritizing ETHA’s established liquidity and people prepared to simply accept extra complexity to earn staking revenue via ETHB.