Merchants see dovish edge to Warsh feedback
Information from TradingView confirmed $BTC/USD holding most of its reclaimed floor after bouncing at $80,000 on Thursday.
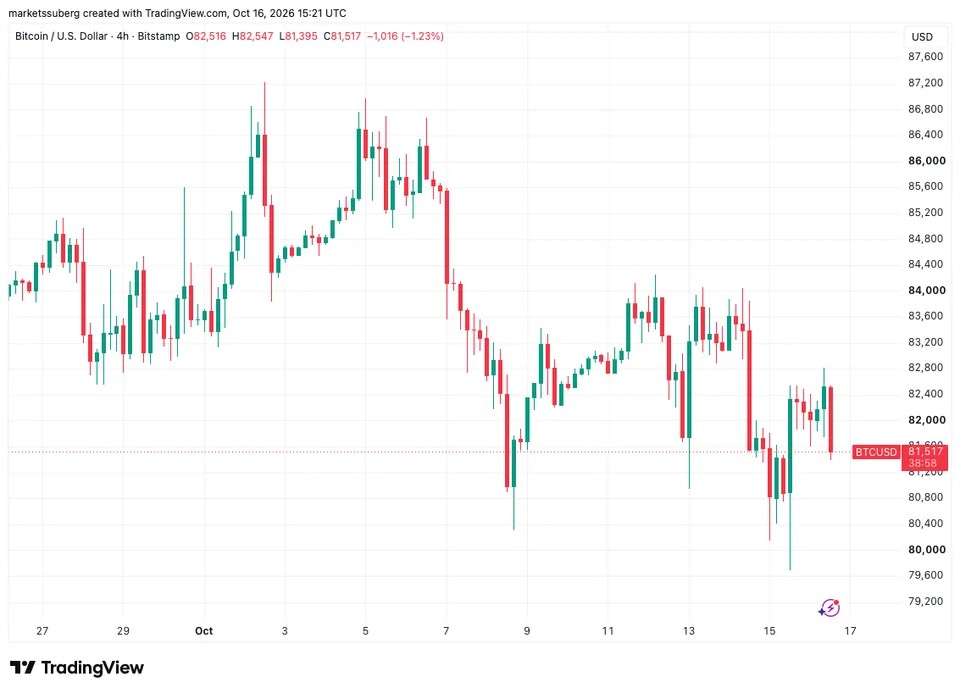
$BTC/USD four-hour chart. Supply: Cointelegraph/TradingView
The sooner decline adopted a weeklong sell-off in South Korean tech shares, though Friday’s Asian buying and selling session introduced some aid. The KOSPI Composite Index closed at 5,668, up 2% on the day however nonetheless down 8.3% for the week.
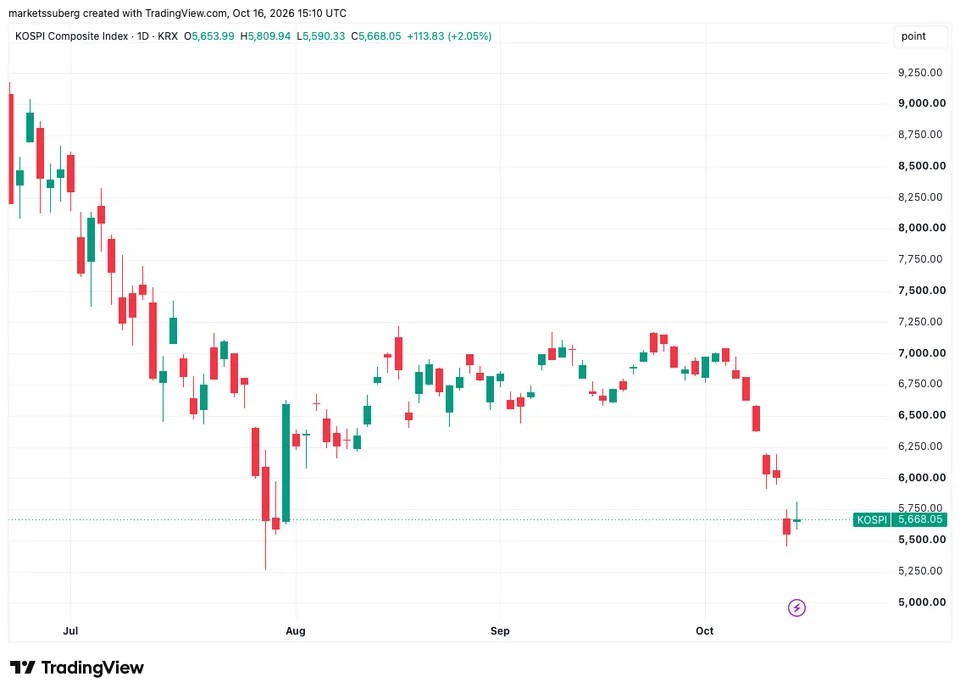
KOSPI Composite Index one-day chart. Supply: Cointelegraph/TradingView
US shares largely prevented the sell-off in Asian markets however have been blended on Friday, with the tech-heavy Nasdaq Composite Index down 0.5% and the S&P 500 up 0.5%.
In the meantime, Federal Reserve Chair Kevin Warsh provided buyers some aid by avoiding any point out of additional interest-rate hikes throughout a dialogue with Worldwide Financial Fund (IMF) Managing Director Kristalina Georgieva.
“I don’t prejudge conferences. I don’t imagine in saying now what I’d do on the conferences that we’ve within the steadiness of this 12 months,” he stated.
Markets appeared to take Warsh’s tone as a dovish sign on charge hikes. Information from CME Group’s FedWatch Device confirmed the chance of a 25-basis-point charge hike in October falling to fifteen%, down from 27% yesterday.
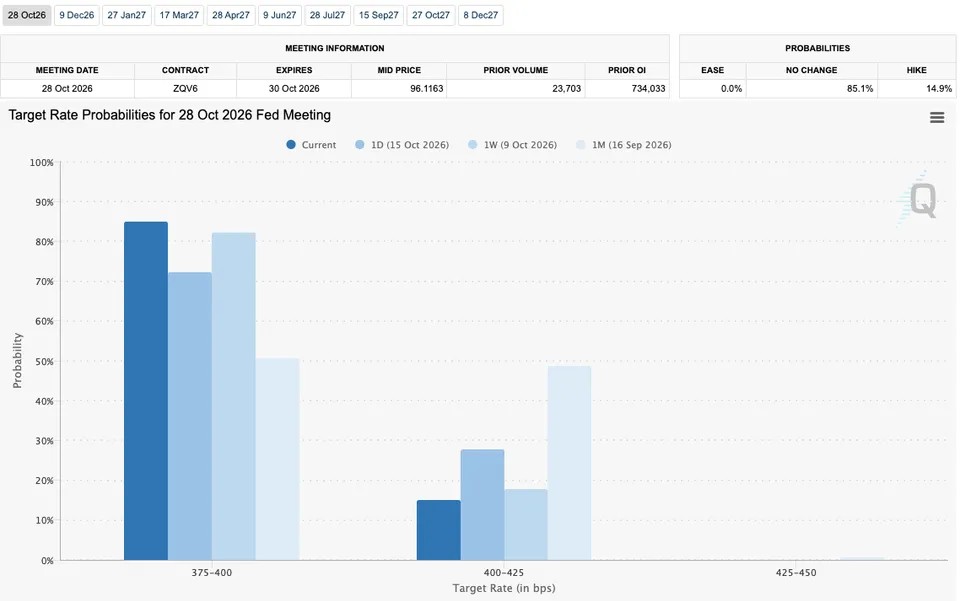
Fed target-rate possibilities for October FOMC assembly (screenshot). Supply: CME Group
Economist Robin Brooks urged that stress within the AI sector, a key driver of the Korea sell-off, might be on the coronary heart of the Fed chair’s extra aloof strategy.
“Warsh gave no indication the Fed’s in any hurry to hike, so the October assembly is now just about off the desk when it comes to a hike,” he wrote in a weblog put up, including:
“What’s serving to the Fed is fears of an AI blow-up, which is making markets extra receptive to a dovish message.”
US bond yields eye rebound as shares halt upside
Elsewhere, US bond yields started rising as shares steadied, prompting solutions that the US treasury could finally be pressured to decide on between taming the bond sell-off and maintaining shares bullish.
The US 10-year yield stood at 5.07% on Friday, having briefly tried to reverse greater, reaching 5.13%.
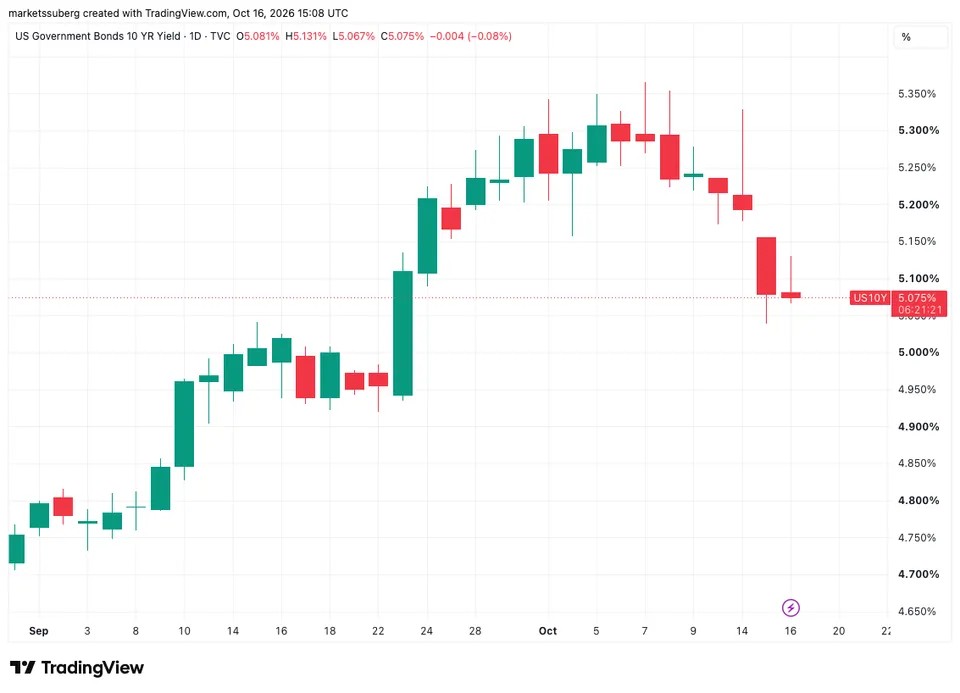
US 10-year bond yield one-day chart. Supply: Cointelegraph/TradingView
Market commentator The Kobeissi Letter famous that inventory weak point has been the only real supply of bond-yield corrections since August. In an X evaluation printed Thursday, Koebissi urged equities could also be in a paradoxical “‘bull-bear’ market.”
With out the US-Iran struggle, shares could be far greater, it argued, including that persistent inflation was driving investor demand for asset publicity — even because the Fed started a brand new rate-hike cycle.
“Even because the S&P 500 hits 12 months #5 of its bull market, we imagine a steep low cost is presently priced into equities. This low cost has functioned as a ‘stealth’ bear market, suppressing fairness valuations on the planet’s largest and fastest-growing firms,” it concluded, including:
“This backdrop has the flexibility to catalyze a violent rally within the S&P 500 if and when it’s finally priced-out.”
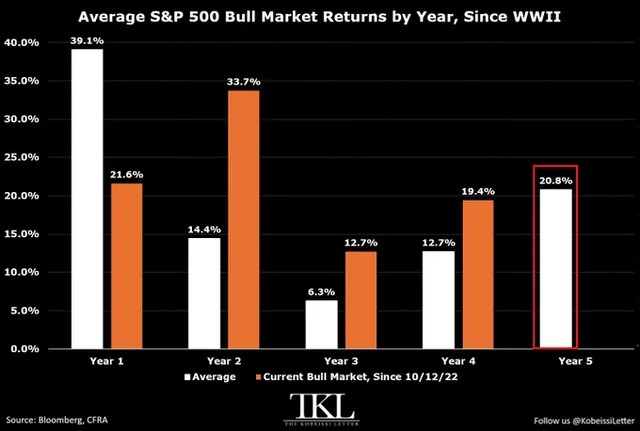
S&P 500 common bull-market returns comparability. Supply: The Kobeissi Letter on X.com