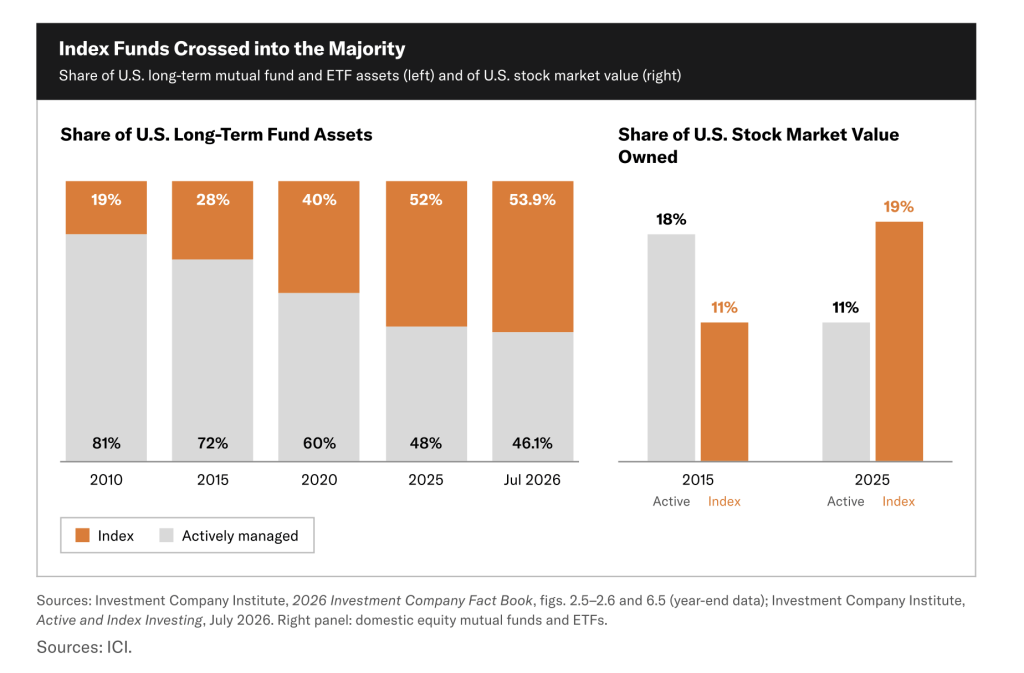
That results in one of many extra counterintuitive factors in Brown’s analysis. The index supplier doesn’t really handle these trillions. Fund managers do. But when an index supplier modifications the businesses on its listing, funds constructed to trace that benchmark usually have to regulate with it. As Brown’s evaluation lays it out, the agency writing the rulebook by no means touches the investor’s cash, however its choices can nonetheless set billions of {dollars} in movement.
The mechanics turned significantly much less theoretical in 2025. The Bitcoin Coverage Institute writer recounts how MSCI proposed excluding firms whose digital property represented not less than 50% of whole property, placing the bitcoin treasury agency Technique squarely within the body. JPMorgan analysts estimated Technique’s elimination might immediate roughly $2.8 billion in promoting by MSCI-tracking funds, climbing to $8.8 billion if different index suppliers adopted.
MSCI finally nixed the proposal, however Brown factors to what occurred subsequent. The agency froze will increase within the variety of shares it will rely for affected firms and deferred new additions whereas making ready a broader evaluation.
Bitcoin Rule Returns Carrying a Totally different Hat
Seven months later, Brown writes, MSCI got here again with a broader check that not singled out bitcoin (BTC) or digital property by title. As an alternative, the August proposal facilities on whether or not an organization has sufficient “working property.” An organization failing the preliminary 50% display screen faces 5 further monetary checks and, if it isn’t already an index constituent, might be excluded after triggering 4 of them. Current constituents obtain buffers and customarily should fail throughout two consecutive annual evaluations earlier than elimination.
Right here’s the place Brown sees a basic downside. His paper says “working property” isn’t a standardized balance-sheet class beneath U.S. GAAP or IFRS, leaving MSCI to categorise every little thing from money and mineral rights to unfinished development, mental property and strategic holdings earlier than the mathematics may even start.
Brown additionally zeroes in on Technique’s bitcoin accounting. The corporate reported $22.8 billion in bitcoin-related working losses in the course of the first half of 2026, in contrast with $195 million in its different working bills. Depend these figures as Technique filed them, Brown argues, and one among MSCI’s flags wouldn’t be triggered. The 23-page paper contends that reaching MSCI’s simulated consequence, due to this fact, requires an analytical reclassification that the session doesn’t disclose.
The Uranium Twist Breaks the Story Extensive Open
Brown’s argument will get significantly stranger as soon as bitcoin leaves the image. MSCI’s simulated deletions additionally embody Yellow Cake, an organization that holds bodily uranium. The Bitcoin Coverage Institute paper then takes the proposed methodology for a spin throughout different capital-intensive companies, illustrating how the identical logic would possibly attain firms constructing satellites or a serious U.S. lithium mine.
Underneath one believable interpretation examined by Brown, AST Spacemobile might set off 4 of MSCI’s flags and doubtlessly be barred as a brand new index entrant. Lithium Americas presents a good sharper instance. The corporate is constructing the Thacker Go lithium undertaking in Nevada, and Brown’s evaluation finds it might additionally set off 4 flags.
Lithium Americas reported $3.54 billion in property in June, together with $2.09 billion in mineral properties, plant and gear. But Brown’s paper exhibits how a restrictive studying of MSCI’s proposal might make a mine nonetheless beneath development look “non-operating” exactly as a result of it’s costly to construct, hasn’t begun producing income and relies upon closely on exterior financing. The larger the unfinished undertaking, in different phrases, the stranger the accounting image can turn into.
MSCI is anticipated to determine on or earlier than Oct. 16, with any adopted modifications slated for its November index evaluation round Dec. 1. Brown’s paper begins with bitcoin treasury firms, however its argument in the end lands someplace a lot larger. When trillions of {dollars} mechanically observe an index, the definition of what counts as an working enterprise is something however tutorial.